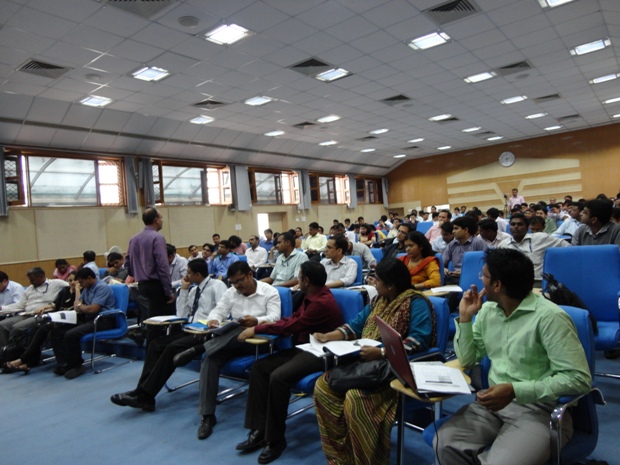
JagoInvestor did the first workshop on Personal Finance. Guess where? It was at Mussoorie and the audience were 120 IAS officers who graduated last year and are posted at various parts of the country. This workshop was done by Me and Nandish at LBSNAA , Mussoorie .
I would like to thanks Nagarajan, who is our reader and an IAS Officer himself, who invited us for the talk. His stand for his community is commendable and worth appreciation. He took a lot of effort in gathering all the officers, organising the talk and co-ordinating it with us. It won’t have been possible without his involvement and dedication towards Personal Finance.
Offline Workshops in Different cities
We have been collecting data of all those readers who are interested in paying a fee and attending our 1-2 days workshops in their cities, we will now start our offline seminars/workshops starting next month in different cities. We would really like to provide the value in these workshops. If you are interested in attending these workshops and want us to intimate you about fees and content before we do it, please register your details here . You can also fill up the form if you can gather a group of 20+ people .
I would like to hear from you what you think about these offline seminars/workshops, please put your suggestions and expectations in comments section. Note that these seminars would be a 1 or 2 day premium seminar which will take care of lot of your financial life related doubts and also give you a proper direction.
Today we will see what is the difference between Gold Saving Funds and Gold ETF’s .
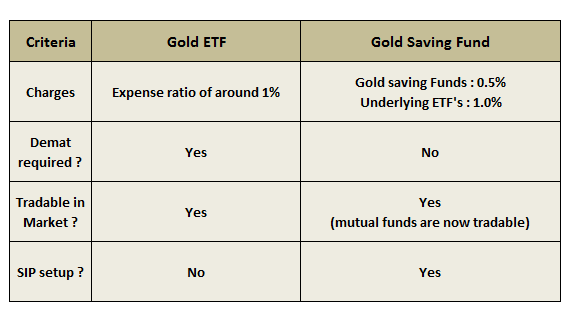
The biggest marketing pitch for selling the Gold saving fund is that one can invest in gold funds without a demat account and can set a SIP for the same, which is true.
However, the alternate option of Gold ETF’s doesn’t not allow investments and/or SIPs without a demat account. But most of the agents hide these details of costs and do not educate their clients on how things work!
Source : Kotak Website
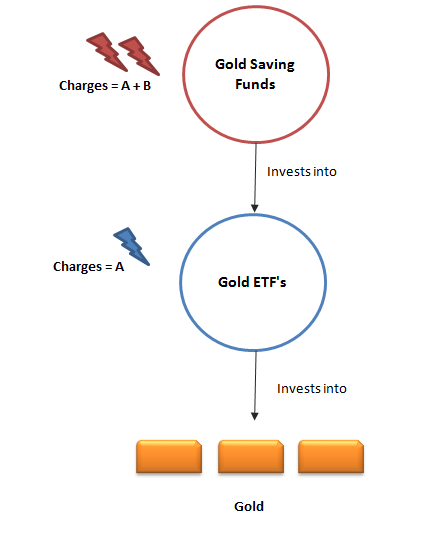
As of today, Reliance, Kotak and Quantum have launched their Gold Saving Funds of Funds. All of these Gold saving funds are almost same. Lets take an example of Reliance Gold Saving Fund, which is nothing but a fund of funds which invest in their respective Gold ETF’s 🙂 Did you know that?
Difference between Gold Saving Funds and Gold ETF’s ?
Gold ETF’s :
Let’s understand this for a moment. In simple terms, these are financial products which invests in physical gold and tracks its pricing on day to day basis. These ETFs have their own expense ratio which is considered very high if compared to US market, but that’s the price we pay to invest in gold electronically.
You need a demat account to invest in Gold ETF and you can trade these ETFs through stock exchange.
Gold Saving funds
Gold savings funds are nothing but mutual funds which invests majority of its corpus (90%-100%) in Gold ETFs (of the same sister company), a small portion might also be in money market instruments or some short term debt products.
For example – Quantum Gold Saving Funds of Funds as per its mandate can invest anywhere from 95%-100% in the units of Quantum Gold ETF’s, and rest in money market instruments and other short term debt products.
But the important point you should note here is that the underlying investment is still gold, but not directly! It’s indirectly through gold ETF’s, and now as there are two layers in between, you pay charges two times!
So you pay charges for Gold saving funds and also for gold ETF’s, this part is generally not revealed by the agent who sells you these Gold saving funds. Also for the gold saving funds there are high exit load’s 🙂
So which one is better and which one you should choose?
We can’t make a general statement that one is good and the other is bad, because it’s not like that. If someone does not have a demat account and wants to automatically invest in gold each month through SIP, gold saving funds are the best option.
But for someone who is conscious about the expenses and can invest through his demat amount each month, Gold ETF’s are a good option.
But high charges will surely hurt in long run! One important point is that do not confuse gold saving funds with “gold mutual funds” which are mutual funds investing in gold mining companies, they are totally different.
Conclusion
A lot of investors are lured into these gold saving funds without giving any information on the charges, which is not right. Gold saving funds over a long-term can really eat away your returns because the high charges will cut a big pie out of the returns earned.
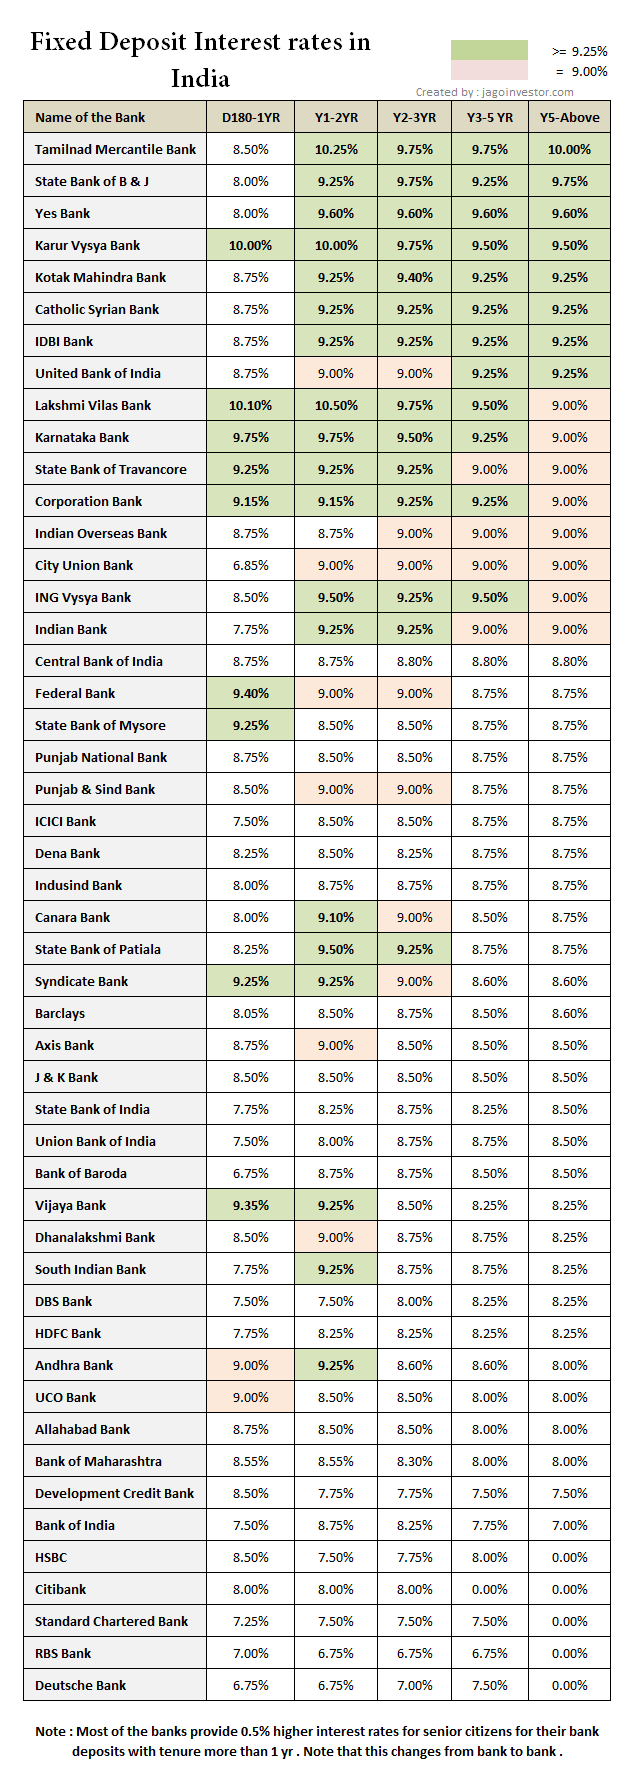
Do you know which bank in india has the highest fixed deposits interest rates ? But before that, let me ask you – Do you know what is the interest rate of your Fixed Deposit ? If it was opened a few years back, all you would have got is around 6-8% depending on the bank and tenure. But today its a different scene! . Fixed deposits interest rates are high these days and you can observe one of the other bank announcing fixed deposits interest rates revised each month and in range of 9-10% . I will show you a snapshot of various banks Fixed deposit interest rates with varying tenures.
For simplicity purpose, I have not included tenures of less than 6 months . See the graph below . Green color represents interest rates higher than or equal to 9.25% . Pink represents exact 9% . The banks mentioned in the table below are Tamilnad Mercantile Bank, State Bank of Bikaner and Jaipur, Yes Bank, Karur Vysya Bank, Kotak Mahindra Bank, Catholic Syrian Bank, IDBI Bank, United Bank of India, Lakshmi Vilas Bank, Karnataka Bank, State Bank of Travancore, Corporation Bank, Indian Overseas Bank, City Union Bank, ING Vysya Bank, Indian Bank, Central Bank of India, Federal Bank, State Bank of Mysore, Punjab National Bank, Punjab & Sind Bank, ICICI Bank, Dena Bank, Indusind Bank, Canara Bank, State Bank of Patiala, Syndicate Bank, Barclays, Axis Bank, J & K Bank, State Bank of India (SBI), Union Bank of India, Bank of Baroda, Vijaya Bank, Dhanalakshmi Bank, South Indian Bank, DBS Bank, HDFC Bank, Andhra Bank, UCO Bank, Allahabad Bank, Bank of Maharashtra, Development Credit Bank, Bank of India, HSBC, Citibank , tandard Chartered Bank , RBS Bank and Deutsche Bank . Look at the table below for the indicative interest rates for different tenures.
Note that a lot of banks offer high interest rates for special tenures like 500 days, or 555 days or 1000 days, but they have some restrictions which people dont know – some of them are
Some banks have provision, if rates increased in future, you can not apply for extention at higher rate of interest, instead you have to close that account and apply for new one.
Automatic renew not possible.
Upon maturity, you will not be able to get overdue interest.
Sometimes, you cannot premature close the deposit. however, these conditions vary from bank-to-bank.
There are some patterns we can see in area of fixed deposits . here they are
Fixed deposits with high interest rates for almost all the tenures are not the heavyweight banks, but the new generation banks, they are Tamil Nad Mercantile Bank, Karur Vyasa Bank, Kotak Mahindra Bank, Lakshmi Vilas Bank and others
Most of the banks provide 0.5% higher interest rates for senior citizens if the tenure is more than 1 yr . But if tenure if lower than 1 yr, the interest rates are same for senior citizens also . This is widely true , but some banks like Axis bank , SBI bank , ICICI Bank and HDFC Banks gives 1% higher interest to senior citizens.
Most of the foreign banks like Citibank, RBS , Standard Chartered has low-interest rates in range 6-7.5% . This is unattractive during these times when other banks are giving higher rates .
Low and Medium risk appetite investors can cheer
For investors how find themselves not too comfortable with equity and for those who want to park their money for few years without taking any risk and earning some good return in range of 9-10% , Fixed deposits are very good options.
The only point is if you are in high tax bracket, most of the returns will go in tax, but for investors who are in lower tax bracket of 10% or below the permissible limits , they can look for these options without much thought . These fixed deposits were for the year 2011 , but for most part of 2012 also these bank fixed deposits interest rates will be applicable .
What is the equity and debt exposure of your portfolio? How many different companies have you invested in through mutual funds? And do you know of any tool with great UI and simple features that can help you analyse your mutual funds and stocks in detail? If you wondered that there is no such website which can do such analysis and that too for FREE, I am happy to introduce you to moneysights.com. It does it all that for you and much more…
From a few months, I am in touch with moneysight’s team. At that time they were still building their product and were trying to solve some key issues which investors face today and I knew from beginning that users will like their product when it goes live. Just a month or so back when their product was in beta mode, all the Jagoinvestor readers on email (see sidebar for subscription link) received the beta invitation from moneysights and they got a chance to use their tool exclusively and in advance than others.
The reason why I want to know about moneysights is because they aim to solve 3 key problems that is faced by common investors in India. These problems have played a crucial role in ensuring that Mutual Funds & Direct Equity investments remain under-penetrated as fas as mass market retail investors are concerned. I have described these problems below from Mutual Funds point of view –
Problem 1 : Choice & Suitability
There are 4,000+ of Mutual Fund schemes in the India today. If one includes the variations & scheme options like Growth, Dividend, etc. These schemes are broadly classified in 10+ types like Equity, Debt, Balanced, MIPs, ELSS etc. Most of the average retail investors don’t understand or demand so much of choice and option. A large number of schemes not only adds confusion to the decision-making process but also often results in postponing our investment decisions (i.e. taking actions).
If the quantity of schemes in the market is the first problem, then knowing the suitability of the scheme to an individual is another problem to be cleared? Not every scheme is suitable to every type of investor. An ICICI Prudential Discovery or IDFC Premier Equity may have given great returns & hence they command a 5-STAR return rating but how many of us know that both of them primarily invest in stocks which most often may not be Large-cap stable businesses. And hence they may not be suitable for someone who is risk-averse or someone who is just beginning to invest. Wouldn’t investing purely on return ratings may bring-in a surprise to the investor when the markets go into a downward trend?
Problem 2 : Construction of Mutual funds portfolio
Reading my previous posts on how to create a Mutual Fund Portfolio or How many funds are ideal to have in a Portfolio, you would have realized that diversification in the Portfolio is very important. But then, why how does one construct a diversified portfolio of 4-5 different Mutual Fund schemes. There is so much information needed to construct a diversified portfolio that it’s definitely a cumbersome task to construct one manually.
For example having a HDFC Top 200 & a Birla Sun Life Frontline Equity isn’t diversification but duplication. They are 2 similar funds & having both of them doesn’t make sense in a diversified portfolio. Look at this jagoinvestor forum question of mutual funds portfolio review and moneysights helping him.
Problem 3 : Tracking of Mutual funds portfolio
After someone invests in a set of Mutual Funds, is there a way to track, monitor & manage the Portfolio in a seamless manner? Most websites do offer tracking services. But then, again people like Venshu had asked about how to get annualized returns so as to compare portfolio performance, sector allocation, etc. so that one can get actionable insights to manage the Portfolio on an ongoing basis that minimizes portfolio risks & optimizes returns. I have used their tracking tool myself and it looks simple and good to me.
Some more good features
Some of you who would have registered on moneysights.com may be able to relate to what i’m talking here. However, if you have not tried it yet, let me summarize quickly on what stood out for me –
1. Fund’s Performance Report Card
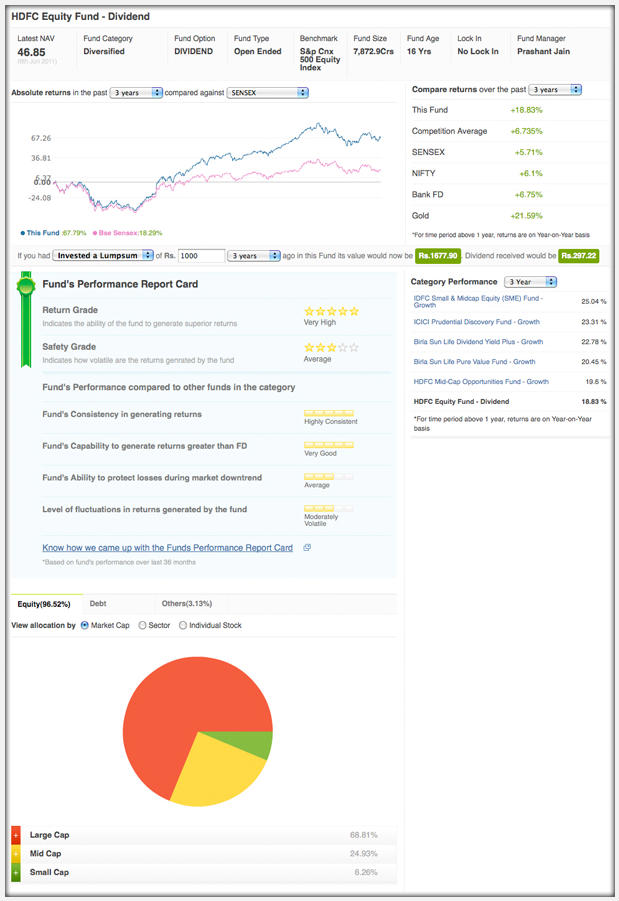
Moneysights allows you to get more information about a specific mutual fund scheme in a quick & simple way. Just go to the Find Mutual Funds section where you can search or browse for specific Mutual Fund schemes. Opening the detail page of a Mutual Fund scheme like HDFC Equity Fund would allow you to see –
A unique way of portraying Fund’s Performance through Fund’s Performance Report Card – also notice the no-use of financial jargon
Performance Comparison with fund’s benchmark, SENSEX or NIFTY – notice the lack of importance to NAV & prominence to performance chart w.r.t. various benchmarks
Return Comparison with SENSEX, NIFTY, Category Average, etc. in tabular format during different time periods
How much your money would have grown had you chosen to invest in this scheme – notice the actual amount of dividend you would have earned
Mutual Fund Category Performance comparison within different time-frames
Portfolio composition of the scheme in terms of asset class, market capitalization, sector exposure & underlying stocks
So, all the information you require for knowing how good or bad a Mutual Fund scheme is available within a single-page interface.
2. Portfolio Health
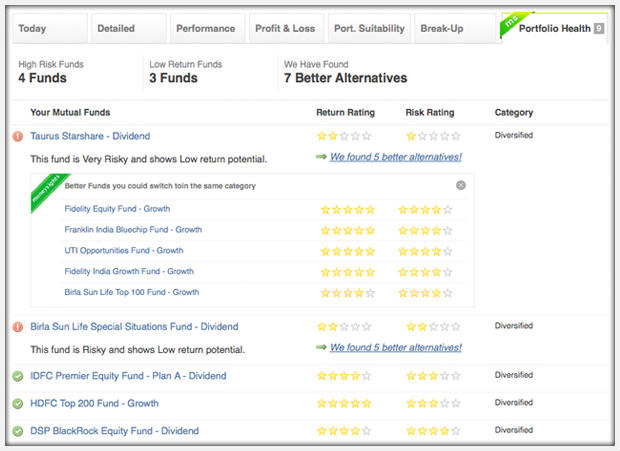
Now this is another valuable feature. Many a times, readers have posted questions on forum about specific funds that they have invested in. Questions like shall I stay invested in (say) a Reliance Vision Fund or Sundaram SMILE Fund which probably used to be good performers at some point in time but are not the best ones today. Does it make sense to redeem & divert the investment in some other fund in similar category? Portfolio Health answers this.
The way I understand moneysights is doing is they find a scheme which belongs to same category as you have & check if there is a scheme which has performed better – i.e. taken lesser risk but has offered more returns. If they are able to find a better option, they show these options. Let me know what you feel about this in comments section.
3. Get a Portfolio
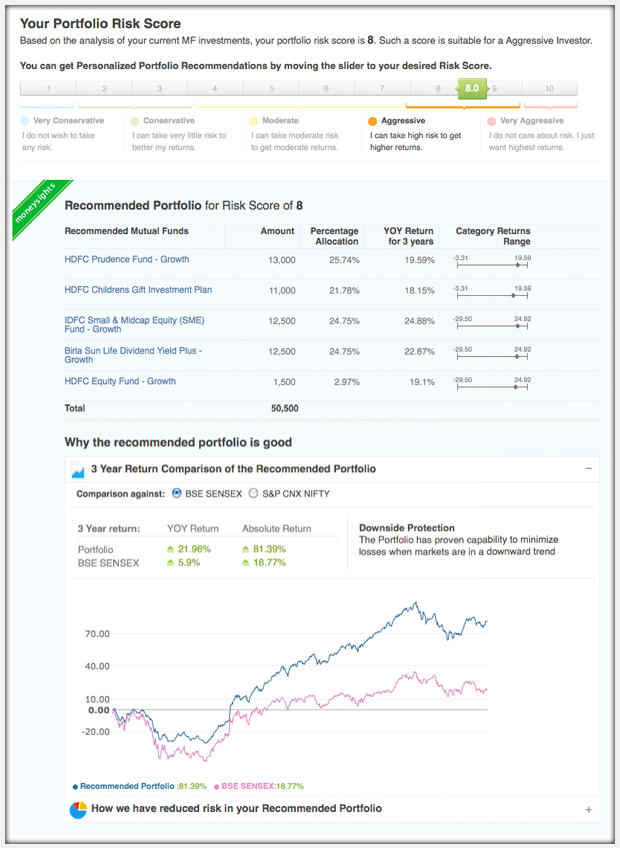
This is going to be useful for readers who want to start their investments from a scratch all over again or re-align their portfolio to their risk appetite. All you have to do is select a risk profile you can identify with & moneysights displays a portfolio of Mutual Funds which is appropriate to the risk profile selected along with how much exposure you should take in a specific scheme. I personally spoke to moneysight’s team & they mentioned that they give more importance to downside protection capability while choosing the funds & portfolio is constructed following best practices of portfolio management that control portfolio concentration risks. They also recommend funds which have proven history of performance & have a minimum AUM under their belt.
If you play around with this engine you would notice that higher your risk score more is the allocation to Equity. You would also notice that the resulting portfolio is always diversified across schemes, fund houses, sectors & stocks. They also show portfolio’s break-up & its past performance against SENSEX & NIFTY that help you understand why the portfolio is being recommended to you & how it’s good.
Other Small but Significant Features that you may like –
While the above 3 stood out for me, you may also like the many things they do differently like –
Letting you enter the amount of Investment & SIP day for accurately tracking your SIP investments.
Annualized returns of the schemes you invest in as well as the Portfolio when your investments are more than 1 year old – a very handy feature for readers who have been looking for XIRR returns.
Dividends that you may have received for your investments.
Updating missed SIP details – You can also update if you missed investing in a specific month for one of your SIPs. Doesn’t it happen sometimes intentionally or unintentionally with us?
By allowing you to redeem Mutual Funds partially or fully, they also let you build history of your booked past profits/losses.
Wishlists for moneysights
There are some of the things which I would personally like to see in future releases . They are
An advanced comparision tool which can show the past performance of the current portfolio
Comparision of two or more mutual funds/indexes in much more detail.
I wish if a user can create his own strategies and run it over the portfolio and see how the strategy would preform over long term.
I also wish if there was a download your Portfolio report in xls and PDF format which I can download and keep it for my record from time to time or just offline viewing . That report can give the overall Report in nice format which is just awesome to look at and worth showoff .
Area’s of Improvement
For most of the return analysis and comparision , it can be done only for the last 5 yrs , I hope if it can be maximum possible .
Their UI is great and neat , but I still feel there are much more things on UI than required and some of them can be displayed on demand (on a click) . What do others think ?
Conclusion
To conclude, if you have feel that you can relate to even 1 of the above problems that I mentioned at the beginning of the post, you would agree after using moneysights that it’s an answer to those problems. I would love to know your opinion on this. Please share it in comments section.
I will teach you how stock scams work today and for that Let me declare something – “After years of study and hard work, I have come up with a strategy which can predict stock markets movement with almost 100% accuracy. Each month I can tell you which way market will move in next 30 days, it can be UP or DOWN and I can guarantee that. If someone needs to see the performance, I can give a free 6 tips trial.” Now what will be someone’s reaction on hearing this? Most probably, some of you will get excited and interested in getting these free tips, at least to check if I am saying truth or not! . Right now I have a big subscriber base with more than 10,000 people (11.5k to be precise) whom I can reach by email. Let’s see how I can create a stock tip scam –
Here is how we will build a scenario wherein you are Ajay who is extremely interested in knowing about the tops which are almost 100% accurate. Ajay is bearing some disbelief in his mind, but due to the trust factor in the given tips he thinks ‘Let’s see what tips Manish gives, they are free anyway and by reading his tips I am not losing anything’.
I start sending you exactly one tip each month and it starts this way:
Tip #1 (May) : Markets are headed UP
Reaction : Markets really went UP in the month of May. Ajay feels good, but still he is confused if its just luck or did It really went up based on my tip . Ajay anyways wanted to just check the tip and how it turns out . He is a bit impressed and he has made up his mind to act upon the tips if 3 consecutive tips work.
Tip #2 (June) : Markets are headed UP
Reaction : Markets after a bit of volatility finally went up and the tip was a success again! Markets are up by great extent, but Ajay feels like a fool to be so fearful and not act on it. But his confidence has started building up. If the next tip also works, Ajay will invest some money for sure based on the tip!
Tip #3 (July) : Markets are headed DOWN
Reaction : Crash! A huge sell off came in the month of July and the 3rd tip in a row was correct. Ajay starts feeling “Oh my god! Looks like Manish really have come up with something amazing which can predict markets” Ajay makes up his mind to “try” next 3 tips and see how it performs!
Tip #4 (Aug) : Markets are headed UP
Reaction : With all the excitement, Ajay has invested Rs 10,000 in the markets to see if he can make some quick bucks! However, Markets are headed down in the starting of the month and all the TV channels are confirming that next Crash is on the way. Ajay is a bit nervous and secretly praying for the tip to work somehow. He wants market to go UP as per the tip. Everybody around him has already sold off and decided to sell of all the stocks, but you are on the other side. You are praying, literally! And here it comes, markets make a turn up side and it makes one of the sharpest come back in 1 week. Ajay is now in profit and he feels like a winner. Ajay’s confidence in my tips is becoming stronger, but still he is not ready to take BIG risks, he needs to solid confirmation that the tips will fall true no matter what, which is about to come .He will invest 40k in the next tip of mine.
Tip #5 (Sept) : Markets are headed DOWN
Reaction : Ajay thinks that he should liquidate all the investments in direct stocks and even his mutual funds. His friends do not think alike and suggest him that he should not go with the tip, but Ajay wants to confirm the tips and wants to see the affect on his investments in real time 🙂 Markets move downside and he is now confirmed that there is really some kind of mega-research done by Manish to come up with the tips using his secret-strategy. Ajay can now visualize how he can become a millionaire soon by subscribing to the tips for next 1-2 yrs. He is just can’t wait for the last tip to show its magic!
Tip #6 (Oct) : Markets are headed DOWN
Reaction : Ajay is totally with the tips now and has decided to use this last one to make some quick bucks, he does some short selling and buys some puts options by finding out how to make money in falling markets. With his confidence in the free tips, he does not lose focus and waits for the tips to turn correct. Markets fall as per the tip and due to his decisions, Ajay has made some amazing money this time. He is clear that he wants these tips at any cost now!
Free tips are over now.
Free tips are over now .
Taking money from the targets – How Stock Scams unfold
Tips are over now, Ajay and many others like Ajay has experienced the amazing tips which really worked. They all get a mail after few days from me.
Hi, you might have already got 6 free tips from me each month, we give only one tip each month, but it’s bound to work. It’s based on our strategy which is based on years of research. If you want to continue getting the tips further. It would cost Rs 50,000 for 1 year subscription. You can expect the same accuracy like you saw in last 6 months.
Disclaimer: The tips are highly accurate and we make sure they are accurate, but we can’t promise it and can’t guarantee it legally. Risk is yours
Ajay is so much impressed with my tips performance and so much drowned in greed, that he subscribes to my offer and pays 2 lacs for the secret tips subscription. The tips start coming from next month. But there is some issue this time! . Somehow, not all the tips are working this time. Some tips work, some does not. It’s not at all accurate like it was before. In reality all the tips are just random tips and Ajay is totally frustrated. He has lost a lot of money because he invested big money each time, thinking it would work!
The truth is Ajay fall prey to a stock scam. Now let me share how all this works.
How this scam works
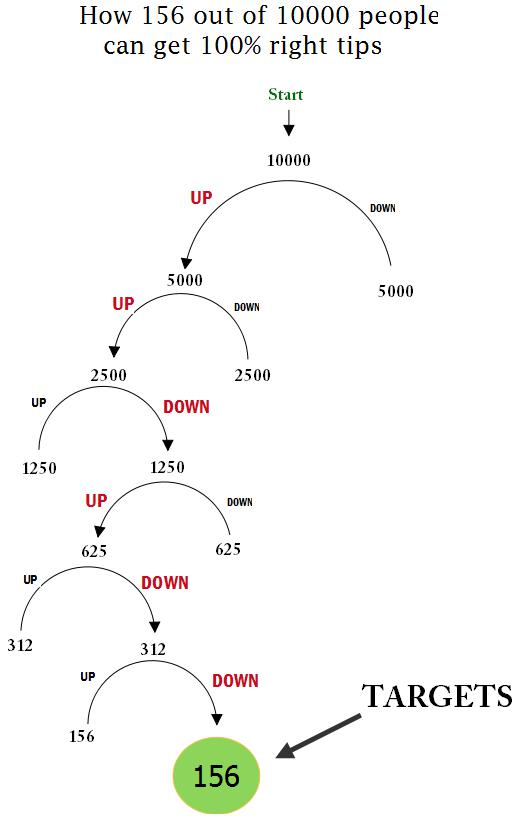
At this moment I have around 10k or more email subscribers and I can send emails to this 10,000 group. I divide this group of 10,000 readers into 2 parts A and B, I send a tip “BUY” to A group and tip “SELL” to B group. One of them will be true for sure. After month is over, I see which tip was correct. If A group was correct, I discard group B and only have people in group A as my final group. This group will be the group which got “correct” tip.
Now I do the same thing again, I divide them in group A and B with 2,500 members each and send “BUY” and “SELL” tip to them. Now again, markets will move UP or DOWN and one of those groups will be right at the end of the month. I again discard the group which got wrong tip. This way I continue doing it for 6 times and at the end I have small group of 156 people who was right all the 6 times and Ajay accidently belonged to his group.
Targets paying for the subscription
Now you can imagine how many people will fall prey to these scams? Even if 20% of the people fall in the trap and are ready to pay Rs 50,00o, it would be Rs 10 lacs in total! Here you can clearly see that out of 10,000 there will always be a group of 156 people who will always get “accurate” tips and the beauty of this strategy is that people who were discarded only get one wrong tip, and after that wrong tip, they don’t get any more tips.
There are many tip providers in real life who claim to give you 90-95% accurate tips with free 1 week trial, If you are getting a lot of right tips, you might be that lucky small group which is their “TARGET” as seen above in the chart. Don’t fall prey to these stock scams. Beware!
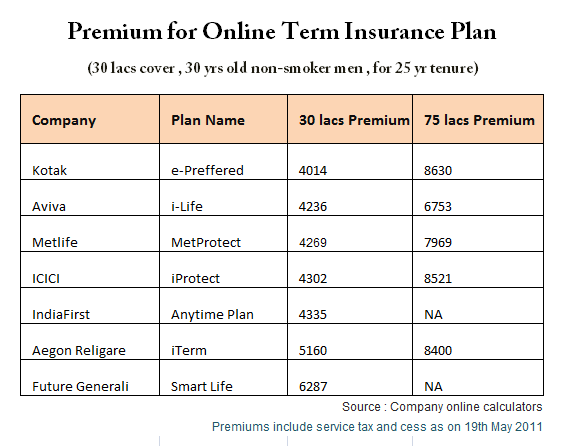
Do you have any idea how many Insurance companies are providing online term plans in India at the moment ? There are total 7 Insurance providers have launched their online term plans and the premiums are highly competitive .
Online Term insurance Plan in India
Aegon Religare was the first company to come up with their iTerm plan which was the cheapest term plan of that time , after that ICICI came up with iProtect . There was a huge response for these policies for cheaper premiums , but both the companies didn’t meet the customer service expectations of customers. A lot of readers even on this blog bought policies from Aegon Religare and ICICI , but faced horrible service when it came to getting policies on time , communication with customer care and its officials , mess of documents etc . A lot of readers suggested that they will never recommend other to go for it.
On the other hand there were customers who didnt face any issue and they got their policies on time . They are recommending others to go for it . However their numbers are smaller than those who faced bad experience. Bad customer service is not desirable by any customer , but I think we can see it improving over time with increased competition and with more better processes . Right now seven companies have come up with online term insurance plans and I am sure more companies are in process of launching it soon . I am not sure if LIC would join them in launching the online term plan , because their offline network is so big and dependent on non-term plans
How Online term insurance plan works
Step 1 : Offline
You go online and calculate your premium , then you start the process of buying the policy and submit your name, age , tenure , sum assured and medical information which affect your premium . After all this you get a premium quote and you pay it online . Most of the people take the premium amount very seriously and believe that its final premium , where as it’s not the case .
Step 2 : Online
After you have paid the premium, there are few things which are yet to be completed . You will get a mail from company or get a call from company that some representative of company will come to your residence and collect the important documents , the documents are also required for KYC . As per your age and given information , the insurer can decide if you will have to appear for medical test or not . If there is anything wrong in medical examination which can affect the premium (increase companies risk of insuring you) , then they can increase the premium (loading) . You can then decide to continue with them by paying the additional premium or cancel the policy .
Update – Apart from Kotak epreffered, Aviva ilife , Metlife metprotect, ICICI iProtect, IndiaFirst anytime Plan, Aegon Religare iTerm and Future Generali Smart Life there are 3 more online term insurance plans introdued in the market which are HDFC Click2Protect, DLF Pramerica – UProtect and Edelweiss Tokia – Life Protection
Comments ? Do you believe in online term plans ? What can motivate you to buy life term insurance online ?
Are free advises costly ? A lot of people in their early life get lots of advice from friends , family and relatives regarding money and other area’s of life . Some of those advises are great, but some are disastrous and you might have the “why did I take that advice ?” kind of feeling . Subra has done a post on worst investment advice and I really liked the sharing which happened there . I think a lot of readers here will relate to those worst advises, because the same thing might have happened to many of them . Lets look at some of the worst advises people have got (i am copying it from the comments section on his blog) . Please share your worst advice in comments section here , It would be worth reading and learning for others !
Ashok say –
Making me buy LICs Jeevan Shree in 2001 (36000 premium per year for 12 years). If I had invested the same 3000/- in a monthly SIP in HDFC Equity fund, I could have afforded a BMW now
Bigtimeloser says –
my worst investment advice was people asking me to do engineering. I had to take it up because i knew nothing about anything else.. Coming from a rural background with a good +2 score I had to do what everybody else was doing..
Iarab says
In 2004, I have been sold a ULIP (Rs. 10,000 annual premium), with an asset allocation of 50% each in ‘Liquid’ and ‘defensive’ schemes. I have been told that ‘liquid’ means ‘money is readily available’ & ‘defensive’ means ‘you will not incur any loss’. The result, after 7 years now, is that I am yet to recover my principal invested (Rs. 70,000), where as my ‘financial advisor(!)’ has graduated from a second hand Bajaj Chetak to Santro i10!
Krish says
One guy from the brokerage firm roped me into F&Os. Rosy picture was portrayed that I can earn thousand(s) a day. The lure was somuch that I borrowed money to trade in F&Os. After first three days I realised that it is gambling and addictive. My risk appetite graph was always up on each passing day to reduce loss and ever hopeful of making the kill. The reality dawn after a month into the trading and losing all the borrowed capital. More than losing money, the mental tension was too much to bear.
Jayant says
“Buy LIC, buy PPF. They are safe investments”. This is when I just started earning at age of 21. If I had started SIP that time, by this time I could have god good corpus. I did not know what seems safe is how badly it is being eaten by Inflation. How I rue !
Vimod says
I have been saddled with a lot of useless endowment policies and whole life plans from LIC of india. I pay a premium of Rs 1.4 lakhs per year as premium for the above insurance policies for a total coverage of Rs 18 lakhs. I will be surrendering
most of it in six months. I try to educate people about buying term insurance policies and not to trust these LIC agents blindly.
Rakesh says
My broker made me buy lokesh machines in Nov,2007. He said that the Big Bull RJ is going to buy/increase his stakes in this company. The price then was 140 and now its 40. I wonder will it even reach that levels ever again ?????????
SS Says
I got an advice to buy a ULIP from a so called friend-expert. What did I do…got rid of advice, got rid of friend (so-called) and got rid of ULIPs forver. i hate ULIps for personal reasons: I lost my friend (i dumped him), I realised he was an idiot and I was in no mood to take free financial advises from an idiot friend (most dangerous thing in finance).
Do you know of any stock in India which has not moved in last 10 yrs ? Hindustan Unilever is one of them ! . Successful investors like Warren Buffett always advocate the importance of investing in stocks for the long term and not just getting in and out of the stock. But more than investing and holding for a stock for the long term, it is important to zero down on the right stock. Or you might even hold a stock for more than ten years and still make very low returns.
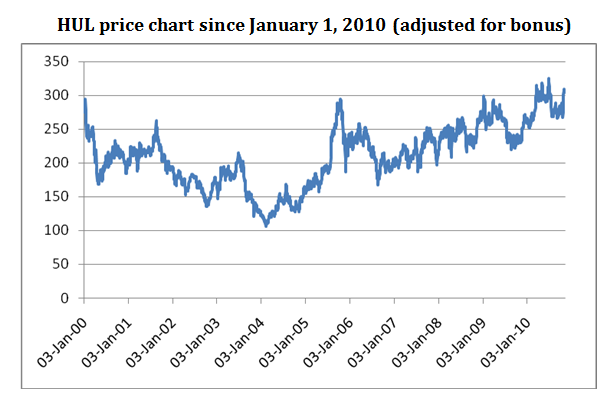
Let us take the example of Hindustan Unilever Ltd (HUL), a company which used to be the largest company as per market capitalization in India, at a certain point of time. But in the last 10 years the price of the HUL stock hasn’t gone anywhere. The stock price touched an all time high of Rs 314.123(adjusted for bonus) on February 25, 2000. This price was never beaten until September 24, 2010, when the stock closed at Rs 314.65. On November 9,2010, the stock closed at an all time high of Rs 318.9. This price was again overtaken in early January (January 5,2011) when the stock closed at an all time high of Rs 325.65. Currently the stock is moving in the range of Rs 300-310.
So the point is that if you were a long term investor in HUL and had invested in the stock in Feb 2000, and held on diligently for 11 odd years, you would still not have made any money on the stock. What HUL tells us is that the buy and hold strategy may not always work.
HUL and the Hindu rate of growth
Raj Krishna, an economist, coined the expression “hindu” rate of growth, to express the slow rate of growth in socialist India, when India used to grow by around 3% every year. Krishna was not a great fan of the socialistic model of development being followed in Nehruvian India. He was a believer in free markets. So looking at this secular trend, year on year, and wanting to take a dig at Nehruvian socialism, which he felt was not working, he came up with an antonym for the word secular (Nehru’s other pet peeve), and so called this growth, the “hindu” rate of growth.
HUL has signified this “hindu-rate” of growth over the last decade. Let us look at some numbers here. The annual sales growth of HUL over the last decade sales have risen at the rate of 6.2% every year to Rs 19,987.1 crore. Profits have grown even slower at the rate of 5.8% every year to Rs 2306.6 crore.
The does not inspire confidence among investors, given that the rate of inflation during that period was at similar levels. So in real terms there has been very little or even no growth in profits and sales. Hence the stock price has been flat.
The main business is facing tremendous competition
Soaps and detergents has been the main stay of the company over the years, and still contributes nearly 75% of the revenues. The company has very little pricing power in this category, given the increased competition that it has been facing. With a slowdown hitting United States, P&G has become aggressive in India. Media reports suggest that P&G is looking to launch its toothpaste brand Crest in India. That should heat up things for Close Up, HUL’s premier toothpaste brand. The cash rich ITC is gradually building businesses similar to that of HUL.
Over and above that there are newer players like Ghadi detergent and older players like Nirma in the lower segment of the market, which have been giving HUL a huge run for its money. To counter this competition HUL has had to constantly resort to price cuts to keep the revenues going in this segment. This is likely to continue in the days to come leading to a very limited pricing power in its premier business. At the same time it needs to keep its advertising expenses high in order to generate a high brand awareness of its products and hope of increasing sales.
New Businesses not contributing enough
During its glory days, HUL’s strategy was to constantly jack up margins. The management graduates who run the company probably forgot a basic lesson in economics. When a company makes ‘abnormal profits’, new competitors enter the arena and drive away margins.
The margins also came from deteriorating the quality of their products. What did not help was the power brand strategy the company decided to follow 10 years back, where in the focus was on 30 odd ‘Power Brands’. The ‘power brand’ strategy prompted HUL to withdraw from a large number of small markets. This has given an opportunity to many small players in the market. Some of these brands like Ghadi detergent are now seriously challenging HUL.
To its credit the company has tried to get into new businesses like selling water filters (Pureit). But these businesses will still take sometime to grow. Also the competition in this market has started to heat up with Tatas announcing their entry with Swach.
What do the analysts say?
HUL recently declared its results for the quarter ending March 31, 2011. While it managed to increase sales by around 14% to Rs 5,022.6 crore. But even with this increase in sales the net profit went down by 2.1% to Rs 569.2 crore. Analysts covering the company came out with reports saying that the results beat their expectations, which is basically a polite way of saying that results were not as bad as we expected them to be.
Given these reasons, those investors who are still invested in HUL, its time they sold out. This stocks is an excellent example of what John Maynard Keynes, the famous economist, said a long time back, “in the long run we are all dead”.
This is a guest post by Sujata Chhaper and the author can be reached at [email protected]
Which one among Reality sector and Banking sector has given more returns in last 5 yrs and 10 yrs with lump sum and SIP way of investing ? Have you ever tried to find out which sectors among indian indices are doing well and which are not ? In this data-oriented article will take you into the world of different sectoral indexes on Nifty, like Bank Nifty , CNX IT , CNX Pharma , NCX FMCG and some more like those . We will see their performances compared with each other with graphs. Note that I have also taken NIFTY as one of the index to compare it with a broader index even though it’s not a sector specific .
Which sectors ?
In this study you will come to know about lump sum and SIP performance of various sectors for 5 yrs and 10 yrs time frame. I have taken the raw data from NSE website and done all the number crunching and graphing to come out with charts which shows you how money has grown in various sectors . I have taken 6 sectors ( Nifty , Bank Nifty , Energy , Pharma , FMCG) for 10 yrs time frame and 8 sectors for 5 yrs time frame (6 mentioned earlier + Reality + Infra ) . We will see the results of 4 different scenarios and will see major learnings from those .
10 yrs performance [Lumpsum Investment]
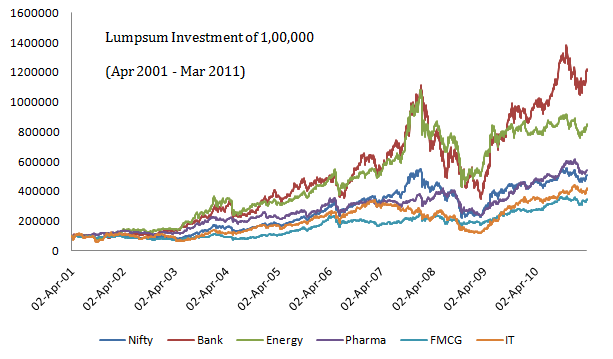
The chart below shows the sectoral performance + Nifty for a lump sum investment of Rs 1 lac in last 10 yrs .
Observations
Bank Nifty was the clear out performer among all giving a 12x return in just 10 yrs . That’s very good return . Energy sector came second and FMCG and IT sector gave the least returns out of all .
Bank Nifty has given 3x return after the crash of 2008-09 . Look at the big spike upwards . Till the crash Energy sector was performing same to same as Bank Nifty , but after the crash, performance of Energy sector deteriorated and it didn’t match up with Bank Nifty.
10 yrs performance [Daily SIP Investment]
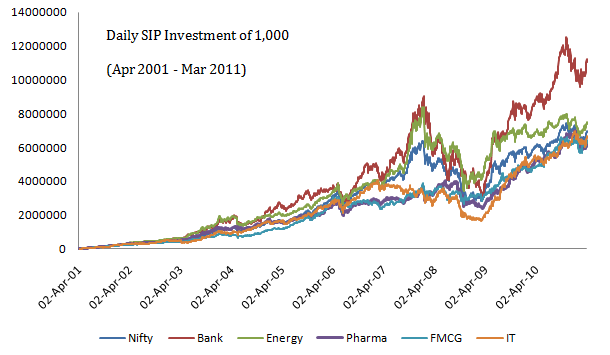
The chart below shows the sectoral performance + Nifty for a daily SIP investment of Rs 1,000 in last 10 yrs .
Observations
The most insight full thing you can see here is that all the sectors other than Bank Nifty has given very close return if one had done SIP regularly . This shows both, the power and weakness of SIP . You can get more returns out of bad sector and less return from the strong sector .
IT sector performed very badly after the crash , but in the recent bull run , it has performed very well and gave superior upside .
10 yrs CAGR returns for lump sum and SIP investments
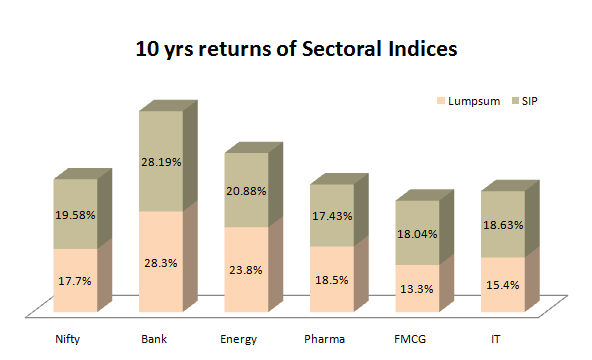
The following chart gives you CAGR return of last 10 yrs for both lump sum and SIP . Note that the values are approx only .
5 yrs performance [Lumpsum Investment]
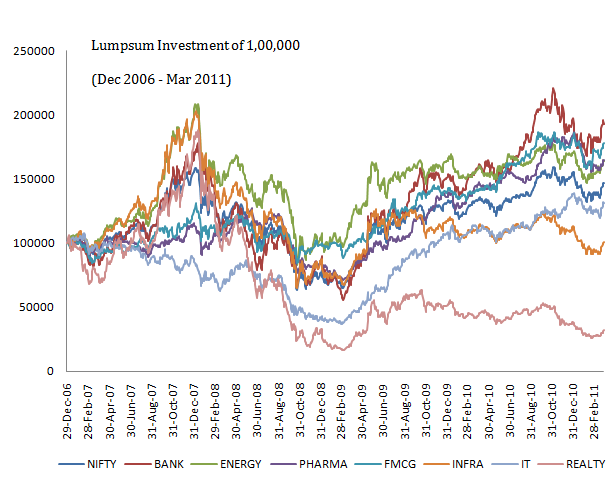
Now we will look at 5 yrs performance of various indices . The chart below shows the sectoral performance + Nifty for a lump sum investment of Rs 1 lac in last 5 yrs .
Observations
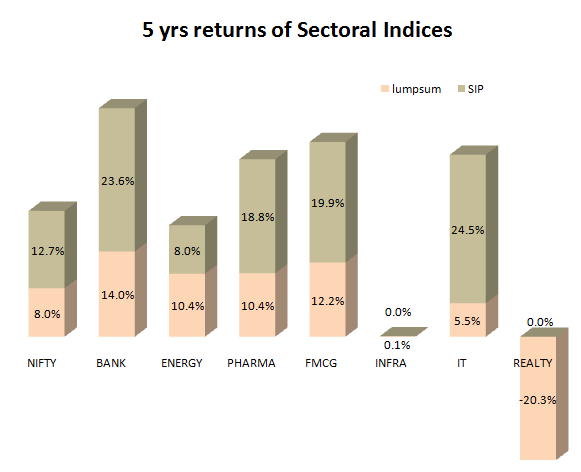
Bank Nifty still leads the pack , the other sectors too performed good and are marginally poor . Nifty , Pharma and Energy come next best .
Reality sector was one of the best performers till 2007 , but then its performance went down and its gave a very high negative return on CAGR basis . When other indices gave above 10% returns on average, Reality index averaged -20% CAGR return .
Energy index has not made much movement in last 2 yrs from 2009 – 2011 , whereas Bank Nifty has doubled .
5 yrs performance [Daily SIP Investment]
Observations
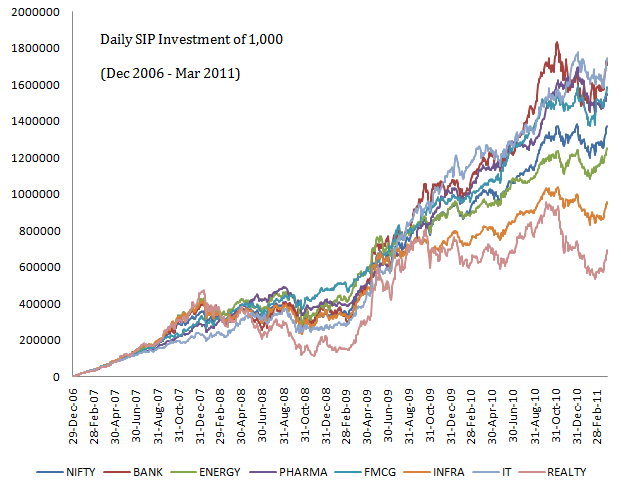
On 5 yrs SIP basis , IT sector has clearly outperformed other sectors and it was very consistent in that . Bank Nifty comes second.
Reality and Infra sector has performed badly and given close to ZERO return in last 5 yrs .
5 yrs CAGR returns for lump sum and SIP investments
The following chart gives you CAGR return of last 5 yrs for both lump sum and SIP . Note that the values are approx only .
Please share what other information were looking from an article like this . Share your comments about the article .
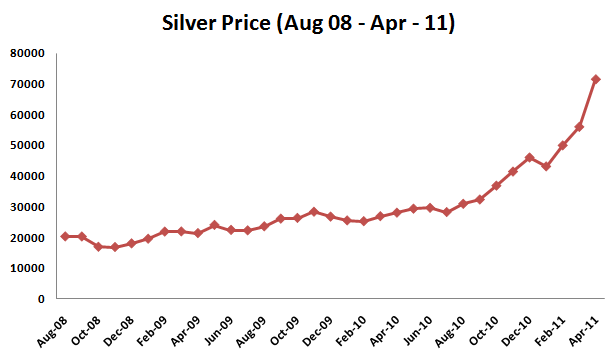
Imagined what gave maximum return in 2011 or 2010? Well, was it Gold, Equity or Real estate? Nope! Hold your breath, it was SILVER and it gave huge returns! It is almost unbelievable that the price of silver as on Aug 2008 was around Rs. 20,000/ Kg, and it went to Rs. 72,000 by the end of Apr 2011, which was a 300% absolute rise in less than 3 yrs. But don’t get too excited, Silver in just 1 week has fallen like anything. From the peak of 72,000 in Apr 2011 end, it went down to Rs 52,000 in just 1 week. Can you believe that? A 28% fall in the prices of silver in just 7 days! Let’s explore more on this.
Gold vs Silver returns ?
Now a days there is a big debate going on different TV channels as well as newspapers that what should a common man buy? Gold or Silver?
In our country, Gold is something which every family buys because of the attraction we have for this metal. On any occasion, gold is the obvious choice. But Silver is not seen the way gold is looked upon. It’s generally limited to not so well off section of the society. This is one of the reasons why middle class or even richer one’s never considered looking at what’s happening in silver and if it can have some potential in future as an investment option. Gold, Gold and Gold was the only option when it came to buying some precious metal.
A lot of people are surprised to hear and see how gold has given fabulous returns year on year in the last decade, but now you would be more surprised to know that for most of the years silver has outperformed gold with good margins in terms of returns. For example, everybody knows that Gold gave 25% return in 2010, but not many know that Silver in the same year gave 80-85% return.
Silver has given 24% absolute return in just one month of April 2011. I don’t think it’s anything other than speculation because that rise was short-lived and in just 1 week (May-‘11 first week), all the gains made in Apr disappeared and prices fell by 25%.
Below is the chart which shows you the monthly price movement in silver for last 30 months. You can see how silver prices exploded in last 4-5 months (2011)
Factors affecting price of gold and silver
1 . Supply and Demand
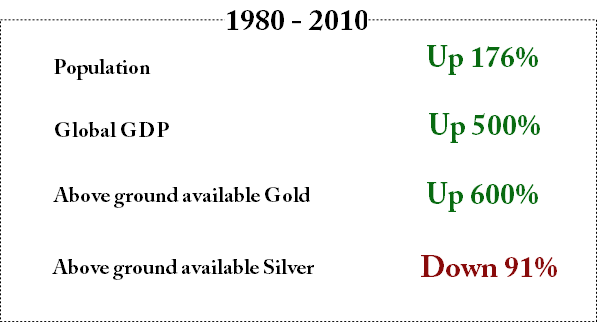
One of the biggest and obvious reasons behind the price movement for anything is its demand and supply in the market. It directly impacts the movement in price. It is estimated that in 1950, the reserves of gold was 1 billion ounces, but by 2010 it increased by 700% to 7 bullion ounces (see the video below)
However on the other hand it is totally different with Silver, in 1950s there were 10 billion ounces of silver, but by 2010, it dropped by huge 95% and its current reserves are only 500 million ounces worldwide. A very obvious reason for this is that gold is mainly stored in form of bars, jewellery etc and its recycled again if required. However silver is also used widely in Industry in very smaller and thin parts which get lost and never reused. In fact, it is not possible to use it again because of its used in lesser quantity and in small parts.
2. Practical use in life
Gold and Silver are very different when it comes to its usage in real life. While both of them are precious metal and often used as jewellery, Gold has a very different image and can be considered as the undisputed king in this area. From millenniums Gold stands the most favourite metal for jewellery, in fact there is some kind of unseen connection which humans have with gold, which cannot be explained. May be it’s the way it has always been and it can’t be changed. But if you see gold as a useful metal, it does not have much to show off. It’s literally not used anywhere other than at a few places.
Silver on the other hand is also used in various industries and holds a very important position. In fact you can see it as “gold” for industrial use. Let me give you more info on this. Silver is used in Bandages, batteries, soldering process, cell phones, computers, satellites, high-tech weapons, laser and digital technology, electronics circuit board, solar cells, water purification, RFID chips and the list goes on.
Silver has more industrial applications than any other metal. A recent report by Hinde Capital says: “It’s the best conductor of both heat and electricity, the most reflective, and second-most ductile and malleable element, after gold.” The white metal is also being put to several new uses like-water purification, air-handling systems and a natural biocide.”
In last couple of decades, Silver is so extensively used in Industry that it’s reserves has drastically gone down. Just to give you an example, in the decade of 1990 – 2000, around 2 billion ounces of Silver was consumed. That’s a lot of silver!
3. Role as alternate currency
Precious metals are always considered as the alternate currency and wealth in pure form in any emergency situation. Gold is a universal currency and not dependent on country or any community.
In times of war, people fear that their assets may be seized and that the currency may become worthless. They see gold as a solid asset which will always buy them food or transportation. Thus in times of great uncertainty, particularly when war is feared, the demand for gold rises. That’s exactly what happened in Zimbabwe lately, where currency is worthless now and people are using gold as alternate currency to buy bread
Recent rise in Silver Prices
You might have heard lately about rise in Silver prices and definitely you might have felt that you “missed the bus”. Let me talk a bit on that. You have already read about the reasons of price rise in silver above. One of the biggest reasons is fundamentals of silver, it is a valuable asset and over a long-term, it’s going to be much valuable because of its use in industry, every industry requires silver!
But other than fundamentals, there are elements of speculation also involved, otherwise I don’t see any reason for 150% rise in its prices in just 1 yr and then a 25% fall in just 1 week. It’s going to be volatile.
To know why the price of silver fell recently , read this article . Please share your comments on Gold and Silver as an investment .