IRDA Fraud Calls – Beware of fake phone calls

There have been too many fake phone calls in the name of IRDA these days to many people. It have been noticed that these IRDA fraud calls are made by anonymous people claiming that they can help you get your money back for your Insurance policies which have become a big headache those those who invested in ULIP’s traditional policies without understanding them and are stuck in those plans now. They know that IRDA is a body which handles them (do they?). At times investors are so fed up with their policies, their life situations and are so desperate to get help that they believe anyone who claims to help them.

So some very smart people starting calling up people claiming they are from IRDA and they can help them in getting back their money back or showing some kind of hope to help them. There are several instances where some people lost more money falling for these calls and believing in them. Lets see some examples of these fraud calls and how investors again believed them without doing their study.

Fraud Case 1 : Deepak lost Rs 25,000

I also Received a call from a number 01206470443 saying that he is from IRDA and I will get a bonus of atleast Rs. 20000- for the insurance policy that I had taken few years back from hdfcsl. However, I had to make an investment of Rs. 25000/- for birla sun life insurance company. but i have no recieved documents of birla sun life insurance company. Any one can tell what I do for my payment back. (link)

Comment

It was very obvious that their was a fraud done with him and he had either signed some cheque or given DD to someone without understanding what he was doing. He must be very excited to get back some bonus (which didnt exist). He

Fraud Case 2 : How S Dash lost 51,000

I received a call from a lady named Riya Malhotra who said she was from IRDA. She said that IRDA is helping out investors in getting back their long stuck up policy funds. I had one Bajaj Allianz policy which I wanted to close. She said she will help me do it if I take a new policy from Kotak Mahindra or Birla Sunlife

She said that this is a five year term, we pay one-time 51000 now (no more premium payment till 5 years) and we will get 50% of the 51000 in 45 days and after 5 years we will receive approx 76000. However we will get a life cover till I attain age of 100. Moreover we can also recover any insurance amount which we are unsatisfied with within 45 days also. It’s already more than 50 days since I made the payment of 51000 by cheque but I have not received any communications from her. I try calling her @ her mobile. No answer.
Please suggest what should I do? (link)

Comment

Note sure whom did she write the cheque for ? There was no rational on choosing a new policy just to get back the money from old policy, there is no relation between both policies.

Fraud Case 3 : How Vikas Lost Rs 3 lacs

Mere pass call aya ki birla sun life me policy one time karane par ek verna car gift ki ja rhi hai , lekin rupees cash dene hoge maine three lakh rupees de diye lekin aaj ek mhina ho gya na to koi bond paper aaya h na hi mere paise sir plz me kya kru (link)

Comments 

I have no idea how a person can believe that if you if you buy a policy , you will be gifted a car ! . Thats too guaranteed ! , That too by giving cash ! .. While this was a fraud call , there was some common sense expected too !

Fraud Case 4 : How Sumit lost his money

In last December 2011 I got a call from IRDA (from number 0120-3050600 saying they are from IRDA) saying that your last policy premium will be recovered as we are from IRDA and we will give one regulatory to Birla Sun Life to return your money back but I’ll not get this amount directly to my account. What I need to do is to take a policy from Aegon Religare for the same amount Rs 36000. This policy will be actually for 16 years with 10 years locking period. But Due to IRDA intervention your policy will be for only 3 months locking period. Your first year premium will be paid by amount from Birla Sun Life policy and I need to pay another Rs 36000 as current year premium and I need to pay next year premium and then 4th year I can withdraw the amount which will be around 1.6L due to some calculation. Over and above that they committed that company will pay agent commission to my account which will be 25% of yearly premium. They will bypass agent from my policy.

They were continuously in contact with me till 18th Jan that I’ll get a separate statement. They know that I can cancel the policy within 15 days of receiving the documents so they were contacting me so that I’ll be convinced and cannot cancel the policy. But after 20th Jan they are neither picking my call nor calling me. So they have found a new way by picking weak vain of customer by giving promise that old lapsed policy amount will be recovered as well you will get agent commission. I had taken this policy bcaz of tenure will be 3 years as well as I’ll get agent commission with last policy lapsed amount.

The person whom I was in continuous contact was Anjali Oberai. Her mobile number is OXXXXXXXX and direct landline number is 0120-4396848. I have called many times on these two numbers to her. Before 20th Jan she entertained all my calls but now she is not picking my call. Also same policy benefits were explained to me by Neha Chaturvedi one of senior person of IRDA from Hyderabad. Anjali Oberai represented Neha Chaturvedias senior person from IRDA from Hyderabad and she came to NCR for some time. Many times I had doubt on them but due to greed of recovery of my loosed last policy amount and getting agent commission I was cheated by them. I know it’s completely my fault. But I would like to take in focus of all so that nobody can be cheated. (link)

Comment

I can see a clear gap in understanding of how life insurance industry works and too much faith in stranger who called up on the name of IRDA . If the policy was really taken from Aegon religare , it should be checked who was the agent in this whole process and nab him/her.

IRDA has clearly issued a notice saying that there is no initiative from IRDA like this 

Insurance Regulatory and Development Authority (IRDA) is a regulatory body established by an Act of Parliament to protect the interests of the policyholders, to regulate, promote and ensure orderly growth of the insurance industry and for matters connected therewith or incidental thereto.

Some instances have been observed by the Authority that general public are receiving calls from individuals who claim to be representatives of IRDA and offering insurance policies of different insurance companies with various benefits (such as offering of scholarship along with policy etc.).

The general public is hereby informed that Insurance Regulatory and Development Authority is a regulatory body which does not involve directly or through any representative in sale of any kind of insurance or financial products. Any person making any kind of ‘transaction with such individuals/agents will be doing the same at their own risk. If any member of the public notices such instances he/she may lodge a police complaint in the local police station.

Sd/-
(Kunnel Prem)
Consultant and Special Officer (Life)

Don’t fall for IRDA Fraud Calls

IRDA is just a regulator for Insurance sector. They do not make any calls acting as mediator between you and company. All they can do is direct a company for some matter or ask them to follow a guideline. But they never work on individual cases and send people to collect money from you. Even if it did , it will never ask for Cash or any kind of cheque on personal names. These kind of calls are purely fraud done by those who know which policies you have (known somehow) and then they just try to see if you can fall for their false promises. Use common sense because making payment to anyone like this, do not pay any attention to these IRDA Fraud Calls.
Which is the best bank for Home Loan ?

Taking a Home loan is a big task in itself and one of the biggest financial decisions. A home loan is the longest debt in our life. At times 10-20 yrs, which makes demands a long term commitment. Each month you have to pay your EMI, sometimes you have to prepay some part of home loan, sometimes you need some documents and visit the bank. There are numerous things to be done during taking the home loan and after taking the home loan, hence you should be very clear that which is the best bank for Home Loan. Without much confusion, it’s very clear that everyone wants to go with the bank which makes your life easy at the time of taking a home loan and even after that. So the biggest question on everyone’s mind is “Which is the best bank for a Home loan?”

Best Home Loan Bank in India

First thing first, you have to be very very clear that their cant is a single bank or loan institution which is perfect for everything and you will never face any issue with them. Also, there is no “best bank for Home Loan” which has always worked for everyone to date. But overall we can always pick some banks which have been better than others on different parameters. You can say that on a high level “Bank A” is better than “Bank B” and this is based on many loan takers’ experience over the years. So now in this article, we will try to understand the difference between different banks and how they differ with each other. We will also see a survey result done with the vast community of this blog and which bank they choose collectively as the best bank for a home loan.

Public Companies vs Pvt Companies

While researching on this topic, the first thing which came to my mind was “all banks are the same, everyone has a bad experience will all kinds of banks, whether PSU or private”. But we have to understand that while some people can have a bad experience with some banks, there are a positive experiences too and we have to see things from a very high level and not judge a bank just based on a handful of bad experiences. The first confusion which comes to any loan taker mind is “PSU bank or private bank?” and based on the experience here is the conclusion.

PSU Banks are good post-loan but not friendly at the time of taking the loan

Private banks are very fast and friendly at the time of disbursing the home loan, they will treat you like a king up-till the loan is disbursed, but once every formality is complete and your home loan is sanctioned, you are a trash to them! As they are extremely aggressive in the marketing of home loans, a lot of people fall for it, Private companies presentation and the way they approach you is good but only till you are not a home loan customer. A lot of times private companies make things easy for you and also bend some rules for home loans. the number of documents they need also is less compared to a PSU bank.

On the other hand, PSU banks are not that great at the start of home loan , their rules are very strict and stringent and they still operate  in the “sarkari” style, however, once your loan process is complete and things start, their afterlife is much easier compared to private banks. The overall handling is much professional and as per the process. In short, they don’t suck your blood every now and then as private companies do.

Private banks are first to raise the interest rates

On the interest rates increase and reduction side, its seen that private companies are first to raise the interest rates after the rate increase from the RBI side, but private banks hide somewhere when there is a time for reducing the interest rates. However, PSU banks are more transparent on this front and much less annoying than Private banks. Also private banks arbitrarily increase the pre-payment charges (  like from 2% to 3%) the conversion fees are also charged heavily if you want to move down to lower interest rates.

Also the changes of fraud at employees level in Private bank is much higher than PSU Banks. I can’t say that PSU banks are not into the bad game, but it’s much much higher in Private banks because of sales pressure and targets. There has been cases of forced selling of home insurance and also cross selling of ULIP’s and other financial products along with the home loan

Which is the best bank for Home loan in India?

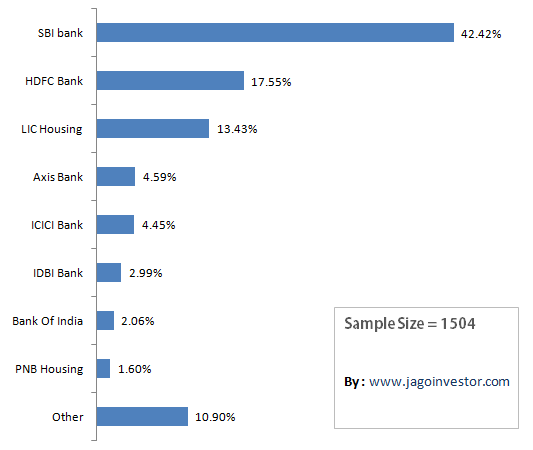
Now there are millions of people who have taken home loan and there are various parameters on which a bank can be ranked like Processing time for a home loan, Transparency in whole process, Attitude towards the customer, Interest rates and pre-payment charges, online tracking of your home loan after disbursement. But there is no ranking of banks on all these parameters. However still you can rank a bank overall as good or bad in total. I ran a survey on this blog and got around 1504 participants to vote for the best bank for home loans and based on that we can judge which banks are more preferable and more trusted. Here are the results.

Best Bank for Home Loan in India (Survey Results)

Best Bank for Home Loan in India - SBI , HDFC or LIC

A good place to look for all the home loan related data (Click here)

Top 5 banks for Home Loan at the moment

If you see the survey above, you can clearly see that the top 5 banks for a home loan are SBI, HDFC, LIC Housing, Axis Bank and ICICI Bank and these 5 banks comprise 83% votes. While a big reason for this can be that these are big banks having a wide reach and has more customers and hence the results are a little biased. But at least you can see that out of 1504 people on this blog, 83% of them have a home loan from these 5 big banks, in which SBI tops the list.

1. SBI Bank

Based on the survey and overall reading’s done over the net and comments section of this blog. SBI bank seems to be the best bank for Home Loan. While SBI Bank still carries the hangover of Sarkari culture and they are strict in the overall process, which means you will have to run all over the bank and many times to get things done, but once the whole process is complete, maybe you will have a smooth experience overall. Things will be easy post home loan process if you need anythings from bank compared to other banks. For those who want to know why SBI is preferred, follow this thread

2. HDFC Bank

Overall HDFC bank seems to be have mixed reviews. Some people had a great experience and some had a very bad experience. HDFC Bank is overall recognized as the bank for the home loan itself. But overall the experience was very very mixed.

3. LIC Housing Finance

LIC housing finance seems to be a decent option after SBI. While they are not that great as SBI, still they seem to be a good choice after HDFC and ICICI bank. LIC Housing Finance has lesser documentation requirements, but one has to run around for smaller details.  LIC seems to offer better rates and also giving the option to fix the interest rate for 5 years. One thing which many people do not know is that LIC reduces the interest rates for home loan for its customers having any insurance/investment policy with LIC by at least 0.25 %, but only if Sum assured of all policies collectively is more than 15,00,000 and all policies should be under the name of the loan applicant.

4. ICICI Bank

ICICI Bank seems to be very very fast and too friendly at the time of loan processing, but once the loan is done, life seems to be hell for most of the people. They are not very supportive most of the times and one gets too frustrated with their attitude. Overall their interest rates are also very high.

5. Axis Bank

Axis Bank is another good option as a big bank. One good thing about Axis bank is that they have NIL charges for any pre-payment. It’s a big surprise that Axis bank was more preferred than ICICI bank overall in the survey. While Axis Bank has few good options, there was one recent case from axis bank which I had highlighted on this blog on how they forced sell a life insurance policy along with home loan, While this was a negative thing from Axis Bank,  we have to understand that good and bad experience are part of all the banks.

So what is the final answer ?

While there are positive and negative experiences from different banks, the clear answer coming out of different comments from readers and survey is that if one has to choose just one name, SBI bank is the best bank for home loans. We have seen most of the votes going to SBI Bank and all the pointers are suggesting that its the right choice.

Which bank do you have home loan with and what was your experience overall from start till the end. Can you share it in for others benefit?

Bangalore Workshop Testimonials and Pictures

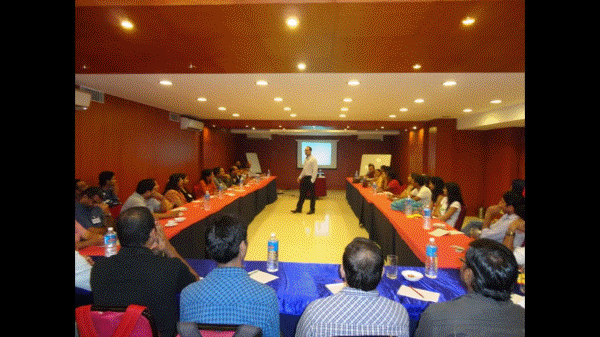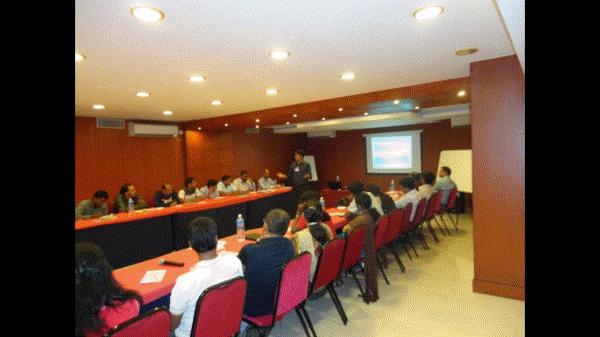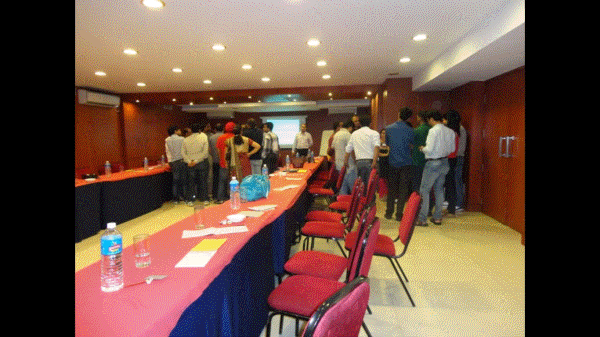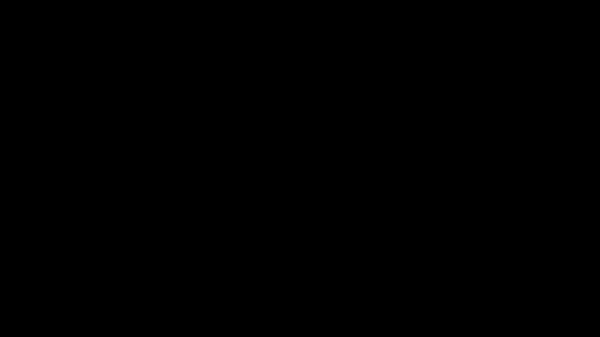
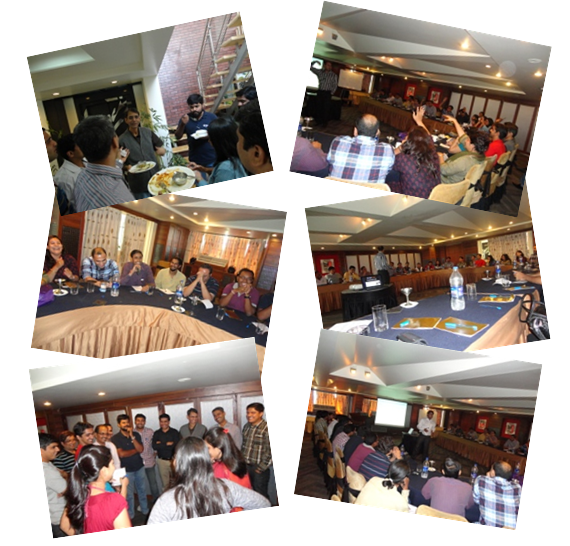
With 45 people in a room at Shilton Royale hotel in Bangalore, the session started. Nandish started the conversation and then it just took off like it was a day made for a great interaction and huge learning for everyone. The session was highly useful for most of the participants and the biggest thing which they could see is “Offline” interactions are so different and some real sharings happen offline when we meet and sit together. The best thing which everyone liked was that there was no regular talk on products because we all know those things already. However it was more of a session where one learns the tricks of a successful financial life and what mistakes most of the people are doing in their financial life.

We shared with the group what we have learned by working with hundred of people and what our experiences are. Overall it was a great day. Here are few pictures from the session at Bangalore.

Jagoinvestor Workshop in Bangalore

Participants Comments about the workshop learning

  • “It is a pleasure to listen to both manish and nandish. The simplicity of which the comcepts are explained is very appealing.The biggest take-away would be – keep it simple silly” – Priya Srinivasan 
  • “Workshop was simple and transforming. I learnt to unlearn some old thinking. Looking forward to mroe sessions and workshop in advanced planning/actions” – Jnanesh Padiyar
  • “I twas a good learning. Passive income, shock therapy are key learnings . Appreciate that you did not try to sell any financial product not even your own book” – Jayaprakash Rao
  • “Your team has given me a new vision, to see what I really want in life, have the knowledge to get it in place and to take the actions required to achieve it. Thank You!” – Deepak Singhal
  • “It was a very good workshop. Really helped me understand my financial life much better.It has taken my financial life to the next level. I also feel there can be more case studies and may be more plays…Thank You !! “ – Pavani
  • “Its a really good workshop. I came here to just hear about financial life but it was not just finance but it is whole life” each and every aspect”. I am going back with some commitment for not just manage the money of what I earn but I need to develop myself, health and improve my intellectual property” – Shyammani Prasad

Video Testimonials

Register for Mumbai and Hydrabad

We are going to conduct 2 more workshops in July in Mumbai (Early July) and one in Hydrabad (Mostly end of July). If you are interested in attending those workshops. Please put your names for the workshop.

Those who were present in workshop and are reading this article, please let others know how it was overall and your comments .

Mutual Funds Performance vs Benchmark Performance

How would you judge whether you have scored good marks in an exam? How do you define “good”? If you had a very very easy test and most of the questions were easy, would you call 80/100 a great score? NO. In the same way, if the exam was very very tough and made everyone cry, but you scored 75/100. Would you call it a great score then? Yes! So the point I want to make is there’s always a benchmark in any area to decide if the performance was good or bad. If you have done better than the benchmark, you did well, else you did bad.  This is exactly how mutual funds are to be judged. You can’t just say a mutual fund has performed bad or good based on the returns it has given in a time frame.

What is a Benchmark?

Each and every mutual fund has a mandate and rule defined on where will it invest and in what proportion. Like if a mutual fund says that it will invest in all the large-cap companies in India, then its benchmark would be mostly NIFTY because NIFTY is the indicator of the large-cap companies. And the whole point of investing in a large-cap mutual fund is that it should give you better returns then NIFTY because you can always invest in NIFTY and get the returns without any fees or risk. So only if a large-cap equity mutual fund beats NIFTY, you can say that it performed Good. Because if it does not then it has performed badly even after you paid him the fees, what’s the point of paying the fees and getting returns lesser than the Index which gives you some returns anyways.

In the same way a Small Cap Mutual Fund would have CNX MID CAP. One can just buy that Index and get returns from it based on the movement of the stocks in that benchmark. A mutual funds tries to take a call on what stocks to select and when to get rid of them to generate superior results and only if it can beat its benchmark, we can say that the mutual fund performed better than it’s benchmark.

Bad Market Performance in the last few years

So in any mutual fund, there is a benchmark and you can say that the mutual fund performed good or bad in a time frame only if the returns from a mutual fund are better than its benchmark for that particular period. Now based on this very simple rule, let’s see some cases. In the last few years, stock markets have performed badly. This bad performance from markets will obviously affect mutual funds performance too. So if a mutual fund has not given double-digit returns, can we conclude that mutual funds are bad investments? No.

Sandeep asked a question related to this 

I was told that HDFC Top 200 is an excellent fund . But I invested around 50,000 in that fund last year and now my fund value is near 46,000 . Is this fund really good ?

This kind of questions come to all the investor’s mind, this happens when you dont know how exactly you should judge a mutual fund’s performance. The only way here to say is HDFC Top 200 did good or bad in the last 1 yrs is to see if its return is more than its benchmark or less than its benchmark and to what extent?

HDFC Top 200 example 

If you look at HDFC Top 200 returns in the last 1 yrs from today (27th Apr 2012), its return has been -9.8 %. Now anyone hearing that kind of return will scream – “Oh .. that’s really bad”. But when you look at its benchmark (which is BSE 200), you can see that its benchmark has given around -12.06% So you can clearly see that HDFC Top 200 has outperformed its benchmark by 2.26% which means that it has done a better job.

Note that mutual funds have stocks as the underlying assets in which they invest, so mutual funds performance will depend totally on stock markets performance and in last 5 yrs, its not mutual funds which have performed badly, its actually stock markets, Mutual funds just mimick the portfolio’s in some manner and the real parameter of how good or bad they have done is to see how they have performed compared to the risk-free benchmark they are following.

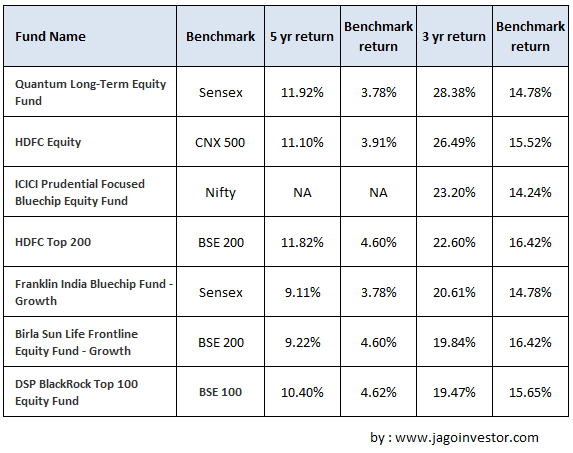
Now coming back to the same example of HDFC Top 200 , it has given around 22.6% returns CAGR in last 3 yrs , but its benchmark (BSE 200) return was just 16.2% , hence you can say that HDFC Top 200 has done a good job and outperformed its benchmark by 6.2% on yearly basis, that’s really a good number.

Escorts Tax Plan Example 

Now lets look at 5 yrs performance of a tax-saving fund called Escorts Tax Plan, The fund has to give -15% return on absolute level in last 5 yrs (1 lac became 85,000) and an agent can say – “Sir – markets were doing badly in the same time, that’s the reason the fund has given bad return’s, in future it would do great” . In this case, all you need to ask is – “Fine, I can understand that market performance affects fund performance but has it performed better than the risk-free benchmark it was following? “

If you look at its benchmark “Nifty”, it has given a 24% positive return in the same period. This means that the fund has performed worse than the index which is totally free, while the fund has not performed even after bring run by professional fund managers. Then what’s the use of that fund.

So now you have a simple rule to judge a mutual fund performance

  • If Fund Performance > Benchmark  – The fund performance was good
  • If Fund Performance < Benchmark  – The fund performance was bad

Note that the duration should be good enough like more than 1 yr at least to say anything and the gap between the fund performance and benchmark performance should also be considered. You can say that a fund was bad just because its returns were 8% and the benchmark was 7.8%. that is very much close and does not conclude much.

Now a fairly good way of choosing a mutual fund is just based on how it has performed in the last many years compared to its benchmark. So I am putting up some top funds which have done very good compared to its benchmark

Some Top Mutual Funds vs Benchmark Returns

The following are some of the very good potential mutual funds for 2012 and they are really doing good overall. Let’s see their returns overall for 5 yr and 3 yr timeframe along with their benchmark returns. You can see some funds outperformed their benchmarks with huge margins. For example, Quantum Long term equity fund has return 28.38% in 3 yrs compared to just 14.78% from its benchmark which is Sensex. Thats 100% more, really brilliant.

Mutual Funds performance vs Benchmark performance

So overall the learning is that if you want to find out some good performing mutual funds, you should be looking if a mutual fund has outperformed its benchmark over several years with a good enough margin or not. If it has consistently done that, you can be clear that fund management is going well.

How often do you look into the benchmark? What else do you think should be looked at while judging mutual funds?

How Husband & Wife can create Magical Financial Life [Video]

What happens when husband and wife take equal interest in their financial life? – It helps in creating an ‘awesome’ financial life. Yes! When both create partnership and put efforts, it helps in creating magical results in their financial life. In the world of personal finance, husband and wife is considered as one entity. They both go out, earn money, help each other in elevating their financial life. We would love to share about two of our client’s rather friends who worked together in designing an awesome financial life.

“Nothing great was ever achieved without enthusiasm.” – Ralph Waldo Emerson

Financial Success of Jassi and Priya

We always tell our clients to live their financial life in a way such that it inspires others. Personal finance is not at all personal if you are confident to share your financial life with the world. It can have results, it will have mistakes but the point is you are proud of the way you live your financial life. This video is of Jassi’s and Priya’s success, we simply played role of a catalyst.

We really want each and every Jagoinvestor reader to create such videos so that we can inspire everyone to live a good financial life. The lesson is if they can do it you can do it too. They really took the Financial Coaching with an open mind and heart, they got on calls on time and are very good receivers. It is their victory that we would like to celebrate it with the world. We asked them to record how they felt after working with us and share it with others, have a look at the video below (youtube link)

Find more about Jagoinvestor Services

Did you listen to their sharing? Did you notice their high enthusiasm and excitement level that they carry with them for their financial life? Did you see how they are on the same page, Did you see how they have created partnership as a couple. Don’t see this video as how great our service is, but really listen to the enthusiasm this couple has shown in their sharing what they created in their financial life. Jassi shared with me once that this video was created in one take and when you see you can experience that it is straight from their heart.

This sharing is really straight from the heart and it is something we would love to share with as many people we can. They are an example that if both husband and wife get together financial success is bound to happen.

May be it’s NOT your cup of tea

May be you think personal finance is not your cup of tea and you do not like to take interest in financial matters. It is not possible that you understand each and everything about finances but at least you can always support your partner when he/she is trying to improve the overall financial life. I like action movies and my wife likes watching romantic movies. I would join her for romantic movies even though I don’t like watching them. It is really not about movies it is about taking interest in those matters which are of interest to your partner. I love reading and my wife hates reading books. From past 1 month she has started reading books, in fact she completed one book which she started and she said she is enjoying reading.

We really have the power to generate interests in our partner if we want to. We can slowly enroll them into financial matters or any matter that we think are important for building a strong future. No need to force or put any compulsion, the more you demonstrate and enjoy something the more they will be keen to join. Take the risk of sharing with your spouse to take interest in financial matters the maximum they will say is NO to you but at least give an honest try to it, give a loving invitation to join you in creating a strong financial future.

Respect your co-pilot

One of the experiences I had was when a woman (one of our client) who got in touch with us for basic financial planning. Initially she gave only her data to us as her husband was not taking any interest in financial matters; he even refused to provide his details. When we delivered the plan to her she showed the same to her husband and he slowly started showing interest in financial matters. I could see how committed the lady was for their financial future. They decided to pay us once again to get a new plan which had combined data of both of them. I could see that this was a golden opportunity for this couple; this moment can be a moment of change for them. I agreed to re-do their collective finances but instead of financial planning I enrolled them in to doing financial coaching.

They agreed and we started the process. On every call wife was a stand for her husband and with each call husband started taking interest in financial matters. He started sharing what needs to be done to take their financial life to the next level, where they need to bring improvements, he started doing the home work that I would give, and every coaching conversation was received by him with an open heart and mind. They really started enjoying the process of wealth creation. They could see that if they play together in their financial life they can achieve anything that they want. Husband and wife are one entity, they hold common vision. I could share with the husband how lucky he is to get such committed wife in his life and to really see her as co-pilot in driving their financial life.

Conclusion

This magic is waiting for you and it can happen in your financial life too.  Forward this article to your spouse if you want their 100% participation in your financial life.  If your spouse is taking equal interest than its time for acknowledgement and to celebrate your partnership. If you need external help go to some planner or a financial coach, schedule a meeting and really take your financial life to the next level. Lastly if you are single you can create similar partnership with your siblings or someone you really trust.

This week action

  • Sit with your spouse and create your financial future
  • Acknowledge your spouse for being with you in your financial ups and downs
  • Take one action together in your financial life and share with us the outcome

Not disclosing your old Insurance policy can lead to Claim Rejection

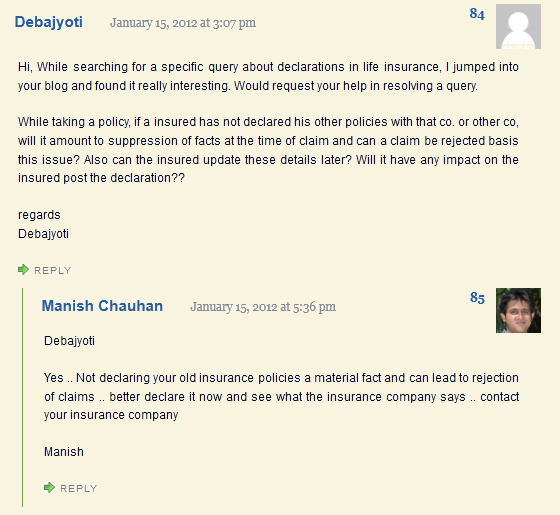
Everyone makes mistakes and are not aware about it ! . A lot of people who buy more than one insurance policies, do not declare about their existing policies to the new company. Some do this because they are not aware about this “compulsory” rule, but some do it intentionally! & there are some who do not pay much attention to it thinking that they will be able to “escape” it and fool the company. However, you should know that companies are very careful about the rules and regulations as mentioned in the policy and declaring your old Insurance policies is a mandatory and important rule. No matter how much your policy sum assured is for, even if its 1 lac, you have to declare it when you take a new life insurance policy (This means term plan, ULIPs with insurance cover, Traditional Policies) . For an example see how Debajyoti was confused on this non-declaration of old policies question and I told him how it was a very important thing to do.

Declare old Life insurance policies while taking a new policy

Today, I am going to discuss a recent case I saw in Crime Petrol (a tv show showing real life cases, must watch) and it is an eye-opener for those how have not declared their existing insurance policies while taking a new life insurance policy. Because in this real life case, a guy family was rejected 1.25 crores of life insurance claim just because the guy did a small mistake, he never disclosed his old policies. Read on –

Real Life Story of Sandip from Gujarat

Sandip was in a lot of debt. His business was not doing well and he was very much worried about his family and what will happen to them. The only solution he could think of is Life Insurance money which they would get after his death, but his life insurance was very very small (few lacs). So he took around 1.25 crores worth of life insurance, thinking that after his death, their family would get all the money.

But there was an issue, a big-big issue. He could not commit suicide, as it was not covered for the first year and his life was becoming really hell and he didn’t want to live anymore. So the only solution was that he should be killed in an accident or some one murders him. He asked his friend to kill him in a way that no one comes to know about it and it looks like murder. This way, he would die and his family will get the life insurance money and his family would live happily.

His friend was scared to death to kill him and really was not able to do it as he was a good friend of Sandip, but finally he killed him on his request. Police came, verification was done and finally Police was able to crack the case and catch his friend. The family figured out about the insurance policy when Sandip’s wife saw the documents in an almirah . The family went to insurance company and asked for claim amount, but the insurance company pointed out the violation of terms and conditions and said that the claim will NOT be paid as there was violation of rules. Family freaked out and gave all sorts of reasons why they should get a claim , but rules and rules. The family filed a case against the insurance company in court, but that was of no use as the court also gave judgement in favour of insurance company.

The family never got any money.
Here is the youtube episode of the Crime Petrol Story I was talking about for those who want to watch it

Have you declared your old policies to new insurance company?

You have probably done the same mistake. If you were holding any endowment/moneyback policy, ULIP, Term Plan or any kind of Life Insurance and then you took a new policy and didn’t declare all the old policies, then after your death, your family is not going to get any money! Please take it seriously.

So your action item is to check with your insurance company customer care about the declaration of old policies and incase you have not given that information at the time of taking the policy, better give them this information, because I don’t think you should be doing that big charity!

Want a Loan ? Pay your phone/electricity bills on time !

Is there a way to determine whether or not it is risky to lend ‘You’ money? How do I know that you wont be a bad customer one day? Very simple – Just look at your credit history and see if you paid your dues on time or not; How many times you were late in making your credit card payment, home loan payment, personal loan dues. This is how CIBIL took birth in India.

But wait – Is this enough? No, we have several other kinds of dues and we make various  payments – those are mobile bill payments (post paid- around 5 crore of them), internet monthly fees (post paid), electricity and other utility bills, even your health insurance premiums. So now very soon you will hear that your mobile bills, electricity bills, internet bills etc are being tracked (actually they are already being tracked) and they will contribute in making of your credit history.

As of now CIBIL, Equifax and Experian (all 3 are credit Beauru) use only your Loan repayments as the criteria for your credit report and credit score, but the Credit Information Companies (Regulation) Act 2005 allows insurance, cellular as well as phone services companies to be counted amongst specified users of credit information companies, therefore, making them eligible to use the database. So very soon all such payments will start contributing to your credit score.

Past records will also affect your credit report

All the major telecom service providers in the country — BSNL, Vodafone and Airtel — are now in discussions with CIBIL for sharing their customer database. So, have you ever declined paying your phone bill? Have you delayed your electricity bill for many months/years or have been late all the time? Do you have this attitude of paying the mobile/internet bills only after getting 2-3 reminders? If the answer is YES, then you better know that all those past sins are staring at you and soon will haunt you.

Be ready to see your home loan or car loan application being rejected because you never paid that vodafone bill for Rs 1,500 and ran off or changed your address? Dude!, your name, photo, past address, DOB is all with them- it will unfold now and if you doubt that- see what CIBIL has to say about it.

“Our systems are capable of handling past payment records as well. If the telecom companies are able to give us the past payment records, we will upload them in the system,” says Arun Thukral – MD, Credit Information Bureau

It’s not clear how much weightage will be put on these kinds of utility bills and insurance premium payments because these are small ticket size in nature and should not be seen in lines with home loan EMI’s and credit card debt which can grow to a big amount. But what do you think about this move and do you think its right?

Jagoinvestor Workshop in Bangalore -13th May [Video]

We conducted a paid workshop recently in Pune called “Design your financial life” . The idea was to take participants beyond financial products and involve them in the thinking process. It was a fun filled day with lot of participation and some really good money conversations which made people really think about their financial lives and how they are leading it till now. Here are some snaps and video testimonials of participants.

Workshop in Bangalore | 13th May (Sunday)

The next event is scheduled in Bangalore on 13th May 2012 (Sunday). The seats are limited and there is a Rs 200 discount for the first 10 people who will apply the discount coupon ACTIONTAKER . They will save Rs 200 on the ticket. It will be a full day event from 9 am to 6 pm at Shilton Royale , 9, 100 Feet Road, | Koramangala, Bangalore 560 047 (Near Sony World). The resigtrations are based on first come first serve basis and it will close by 10th May 2012 .


Spend one day for your financial life

We really want these event to be your event and not just a jagoinvestor event. Its an opportunity to spend a full day dedicated to your financial life. We really encourage people to take those 10 hours for out of 1 full year and just focus on how you want to shape your financial life for future. There will be lot of sharing’s , conversations on money and some exercise’s which will really help you get a deep insights in the area of personal finance.It might be the case that you are interested in this workshop but not registering right now , in that case just let us know that you are interested and still thinking.

Pictures from Pune Workshop

Personal Finance Workshop

We really want to make this workshop a readers event and we want couples to come together so that they can jointly spend a full day in this workshop.

How Jagoinvestor Forum answered 10,000 times !

Most of the readers of this blog do not know whats going on at the other end of this blog which is our questions and answers forum. It’s a place where you can post any personal finance query, whatever doubts you have in mind and the community will help you with answers. You can extend the conversations untill you are fully satisfied and some amazing people on the forum will go miles to fully help you.

I want to take this opportunity to thank few key people on this personal finance forum who have gone beyond expectations and really taken up the full charge of the forum. You can say these people have taken over the forum from me and I am damn happy about it.

Some amazing statistics about the forum

There are close to 2,300 questions asked till date on the forum and close to 10,000 answers are already given, which makes it an average of 4 answers per question asked, which shows a good mix of discussion. I feel proud to say that out of those 2,300 question , all 2,300 are answered, which means 100% questions are answered. The average time it takes a question to be answered ranges from few minutes to few hours . I hardly know any question which was answered after 24 hours of its posting. There are around 1,300+ members on the forum.

Teaching is the best way of Learning

I would like to acknowledge mainly two people on forum who are really amazing and have exceeded the expectations of everyone. They are Ashal and Ramesh . You would really be amazed that they have answered at least 30-40% of the total answers out of those 10,000 answers and they have some really amazing and deep understanding of personal finance topics, which can even beat some certified financial planners ! .

The main idea of this post is to show you that incase you want to excel in the area of personal finance, all you need to do is help people solve their queries, give some time to help others and answers more and more questions from others. This is exactly what Ashal and Ramesh have done and they are the best people I know when it comes to personal finance understanding.

Btw, Ashal is a chemical engineer and Ramesh is a Doctor and this is enough to break your myth that “I cant be great in personal finance because I am not from finance field” . I want to stress on the point is that personal finance is not an area which demands you to be from a finance field. All you need is some passion and that attitude of helping others and learning through teaching others – that’s all . Within no time – you will develop a good understanding of everything 🙂 .

Some really good conversations on Forum

To give you an idea, here are few good questions asked on the forum and you can see the length of the discussions and to what level discussions happen.

Why should you use Forum and When ?

You can ask your question on the forum, for any topic which you need to discuss at length, or anything which you feel should get extra attention and different people views. You can also use the forum to take a second opinion. Just make sure that you have done some homework on your side before asking the question.

If you want your login/password to be created for the forum, you can register yourself on the forum here or just fill up this form and let me know that you want me to open an account for you by filling up this form.

I really want you all to acknowledge the efforts of these wonderful people on the forum and congratulate them. They have really done outstanding work.

I would also kind of acknowledge the efforts of some other heroes who have contributed significantly on forum like BanyanFA , wealthucreate , justgrowmymoney , Shashank , Bharat Shah, Jagadees , Rakesh , Prabeesh , Abhishek and MoneySavingsHelp and many others !

Did you start your Health SIP ?

I begin each day of my life with a ritual of receiving one sms around 5:30 am from my fitness coach Sanjay. The sms reads “I am coming at 6:00 am so get ready” I take a look at the sms and reply “yes”. Initially, I thought that my ritual is to exercise every day, but my real ritual is saying Yes to my coach because, the moment I say YES to him my laziness goes away, my reasons/excuses disappear and I look up to the ceiling of my room and say to myself “Get ready Nandish it’s time to invest in your fitness.” This ritual has had transformative effect on me. I know it is absolutely no fun to wake up in the dark and push ourselves to go for a tiresome run or to hit the gym. But if you really want to cherish your wealth in later years of your life start forming healthy habit of exercising. One of the best website you can explore to get yourself educated on various exercises and diet is http://exrx.net/.

Health SIP

We have a rule if you do not exercise you can’t become our coaching client no mater how much money you have. It is because health is your true wealth. Let me share what we ask to our coaching clients

One of the Questions that we have asked all the people who have worked with us is

Is your well-being on your priority E.g. Do you Exercise/Go for a walk or play any sports? (If the answer is no this will be the first thing we will ask you to start, this will allow you to enjoy the wealth that you are going to generate in life)

Here are some Real Life answers from real people that I have received; I am sharing this so that you can learn from other people’s sharing

  • Yes, I am health conscious and selfish when it comes to health
  • I don’t exercise regularly
  • I used to. I will be resuming soon
  • Yes, for the past 7-8 months I have been going to gym regularly and have a very balanced diet.
  • To somewhat no. I try to maintain a healthy life-style, but fail occasionally.
  • Yes. I am too occupied to start with any of the activities. I am currently working on this.
  • Yes. My wife is an athlete and she pushes/motivates me to stay healthy. I walk every evening and try to maintain weight. I very strictly believe that Health is wealth. There is no use of money at all if I cannot stay healthy. E.g. – Yuvraj Singh – what will be the use of so much money if cannot be cured.
  • Yes. I go to Yoga in my office, daily. I have started this since last 8 months and doing it regularly<90% attendance>.
  • Sporadic exercise. Swim and play badminton regularly.
  • This is exactly what I don’t do at all. All I need to do is start ASAP.
  • Yes. I used to walk daily till 2 months back. Due to back pain and monsoons now it’s held up for two months.
  • I keep doing exercises on and off. More than 3 months back I have taken up Karate. I do that twice in a week, and I am quite sure that I am not going to quit that
  • I hardly do the above, but I will try to make it as a habit very soon.
  • No. My physical activities have reduced
  • Yes, I believe it is. I have started to go on a diet plan and been on it for a couple of weeks now. I have also started to go to fitness centre (tread mill and weights) for a week now. I hope and believe I can continue this.
  • I thoroughly enjoy sports. I play tennis and walk quite a bit. I also do yoga fairly regularly.JMy biggest priority is stay healthy and fit – a fitness freak, if you will. (I wish I had the same drive for money, ever since started earning!

Here is what one of our clients wrote me – “I have reduced my weight by 12 kgs in 6+ months and my BMI is close to ideal though still a bit above. Feel so much more energetic. How is your health investment doing?”

Some Need Shock Therapy

In one of the readers meet held at pune one of our client shared his life changing experience with the group .Once he had to participate in check-up camp organized in his company. He got his tests done and the doctor gave him a very serious look and told him to move to a separate room and relax there for some time. Doctor came after some time and said everything is going to be fine, with this his tension was at its peak. Our client got restless and asked the doctor “what’s the matter?” and doctor said “Diabetes” Our client’s world got shattered in that moment, his heart sank and his throat got dry.

Doctor saw all this and then said, “You are not having diabetes my friend but you are close to having diabetes and so it was necessary for us to give you some shock Therapy.” Our client bought new shoes the same day and was all geared up to take charge of his health. The next day, even with heavy rains, he was jogging in the park…. Do not wait for important things to get urgent, act today, take the learning’s from this experience.

Here is something that I received from my father a few days back

The Dalai Lama, when asked what surprised him most about humanity, answered, “Man. Because he sacrifices his health to make money. Then he sacrifices money to recuperate his health. And then he is so anxious about the future that he does not enjoy the present; the result being that he does not live in the present or the future; he lives as if he is never going to die, and then he dies having never really lived!”

Start your Fitness SIP

Sharing from my personal life, I avoided doing physical exercise for years. My reasons were bigger than my commitment. I broke my reasons 2 yrs back, I hired a Fitness Coach who comes to my home and makes me do a lot of work-out. The fee that I am paying him for his services, I consider it as my HEALTH-SIP. I am familiar with all the exercises and capable to do them on my own but those 5 extra counts that he makes me do is only possible with him. I take this opportunity to thank my coach Sanjay, his commitment is amazing.

Some people…

  • Take better care of their pet than what they do themselves
  • Take better care of their gadgets than what they do themselves
  • Take better care of their car than what they do themselves

Focus more on your health than buying health insurance

When I coach people I see that people are more committed to buy the right health cover and more laid back on focusing on their health! Your body is the only thing which is going to stay with you for the rest of your life. See that you take care of yourself because it is said that your body is the only place you are going to live in for the rest of your life. Connect with your true wealth first, we have heard this since childhood health is wealth but most of us forget this when we grow –up. Getting health cover is important but do not deviate focus from your health, make a commitment you will live your life in such a way so that you do not have to use your health insurance ever. (Unless it is an accident or some other major health issue)

Health Insurance for parents

We interact with many people who want to buy health cover for their senior citizen parents. It really becomes very difficult in getting health cover after certain age and even if you get cover it comes with high premium. More than health cover start giving time to your parents, put 2-3 lacs aside (you can put even more if you have) for them and you can have your own health cover designed for your parents. All they want is your time, your attention and unconditional love. Encourage your parents in doing light exercises or light yoga . One very powerful meditation is conducted by organization called vipassana Meditation, they have world wide centers http://www.dhamma.org/ . My parents have done the same and I think it is the greatest gift we can give to our parents. Enroll your parents for naturotherapy, see that they have proper intake of fruits and dry fruits. See that your parents are not feeling lonely and they are around their friends. Take steps that make them happy this is far far better than saying I am a responsible son I have bought health cover for my parents.

Conclusion

As people are turning towards term plans a lot of people also turning towards joining gyms, going for a brisk walk, hiring a fitness coach, taking advantage of fitness facilities provided by companies. This is your true wealth. I always tell people that at the age of 55 or 60 you might have a lot of money but what if your body is not aligned to cherish that money? Stay healthy, stay committed and stay FIT. Do share what message you got from this post, if you are one of those who are not exercising simply start from this moment. After you complete reading this article do 5 push-ups, climb a stair, just do something in this moment, take small steps, engage in activities that you enjoy doing and change your relationship with health and fitness.

This article is written by Nandish Desai 

This week action ?

  • Do you exercise? Yes or No
  • Hire a coach or join a gym in this week?
  • What one action you can take to bring more life in your parent’s health?