Does Health insurance or Mediclaim Insurance really protect your health ? Ask yourself this question and deep down in your heart you will hear someone shouting , No Idiot ! , There is no policy which can protect your health ! . Health can only be protected by right diet , right exercise and right lifestyle (download this ebook). Unless you are doing any of these your health can’t be insured. So what is Health/Mediclaim Insurance, when it does not protect your health ?
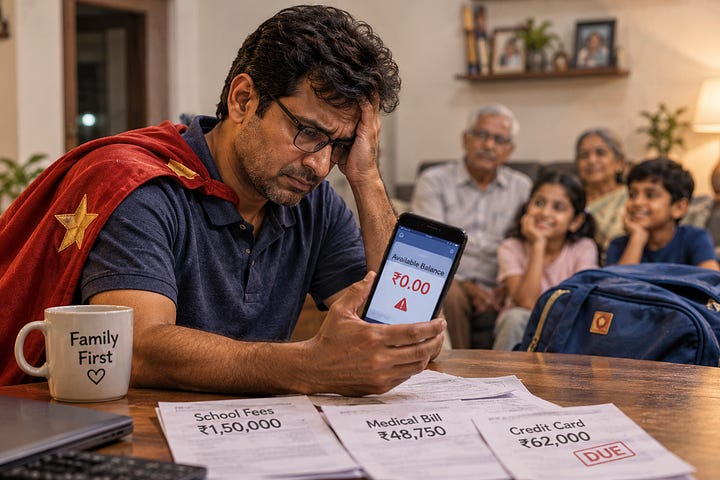
In reality, what we all fail to realise is that Health Insurance is actually “Wealth Insurance” . When you buy a health insurance policy, all you are doing is protecting your wealth from those scenarios which would ask for a lot of money from your wealth. So you have to understand the importance of buying a health insurance policy. (You can buy it from Coverfox website)
I was talking to some one few days back in Goa (Yes, I go on vacations too) who rejected to take a mediclaim policy because of higher premium due to his diabetes. I told him that I hear something out of his decision of not buying a health insurance plan. He was surprised to hear this because he didn’t say anything else other than “I will not take health insurance” . So I told him what I heard.
I told him that I hear from him that he is ready to lose a big part of his wealth in few years if he is detected with any further illness . I told him that I hear that he didn’t want insurance company to pay for his medical bills , but was ready to bear the cost on his own. If he has to spend 5 lacs , he will pay it . If its 15 lacs , he will pay it ! and even if its 30 lacs (after 12-15 yrs) , he will still pay it .
Protecting Wealth is much easier than Protecting Health
I told him that by choosing not to buy a health insurance plan, he is accepting that he is ready to bear a big cost in future incase the situation demands . A lot of people do not think about health insurance like this. While this is the internal truth that the job of health insurance is to protect your wealth and not your health, a lot of people just fail to look at it this way .
So if you love your Wealth , buy health insurance.
For health , you can take other routes like eating right food, physical exercise daily , having a positive and a good life style (see this post from subra) .. But the sad thing is protecting your wealth is much easier than protecting your health 🙂
What are your views on this ? What have you done to protect your health and wealth ?
Hi All,
I am working in a pvt company which gave me mandatory medicliam policy at the time of joining. My wife works in a govt sector and she will get all the medical facililties for the family. Now I have to provide a letter stating I am not getting any medical facility from my current company to avail the medical benefits from my spouse’s firm. But here my HR is not willing to give me the letter. Is there any option t to discontinue the medicliam provided by my company. Please let me know.
HI Anand
You shoudl discuss this with other members on our forum http://www.jagoinvestor.com/forum
Dear Manish Ji,
I have a query related to Pregnancy related expenses in Mediclaim Policy
I work in a big private organisation. I got married around 2 years back and unfortunately we couldn’t go along well and got divorced
Now I am again planning to get married. I want to go for an early child and start a family. In my Company’s Mediclaim policy, in my family details, the details of my old wife are mentioned from last 2 years.
I have two questions
1) Will they change the details if I tell them that i have got married for second time. Is there a provision in Group Mediclaim policies to change the name of wife ?
2) Will I be able to claim the pregnancy related expenses or is there a minimum time period after marriage date that we can claim such expenses
Thanks & Regards
Rahul
1. Yes, they should be able to change it
2. I think it will apply the time limit . It cant happen that the child is due next year and its covered !
Dear Manish,
My grand ma age is around 70 yrs . can you please suggest me some good health insurance for her.
Thanks
Hi Manish,
i took maxbupa health insurance for my father aged 59 ,charged me almost 8500/- only for 2 lak cover. after taking this policy i got call from New india assurance company through citi bank credit cards. actually i dont require it since i have already taken it from max-bupa, but the insurance premium is almost 60% less and there is no co-pay kind of thing in this policy. premium amounts are really tempting. i spent only 2000 for 1lak for my father aged 59, next year his age would be 60, so they may ask him to go for medical tests before approving the health insurance. thats again a big headache. in my case i took at the age of 59, so they dont need any tests for renew of same policy.
so next year i am going to renew this New india assurance policy for 3laks only for 4800/- and going to stop renew of Maxbupa.. that sounds good to me..
What you suggest? Please help me if i am wrong.
Regards,
Sai.
But did you check other aspects like till what age they allow the renewal , the sub limits, kind of coverage they have ?
till 100 yrs, they have full coverage, no co-pay kind of thing.
Health insurance is wealth insurance indeed ! I recommend Aviva’s health insurance plan to everyone. After being a customer of Aviva for three years, I can say that it is definitely one of the safest and best health plans in the market.
I recommend AVIVA online insurance to everyone.
My wife got breast cancer and had to be operated. Aviva paid the entire fees for the operations. Aviva’s health care plan is definitely one of the safest and the best.
Are you not too biased because you had a good experience ? I am not doubting it , but the point is there are many cases where it gets declined too !
Maybe ! It’s always good to read the terms and conditions properly. For example, I checked the hospitals covered under Aviva.
Thats great !
Dear Manish,
Is it true that nationalised banks have group medical insurance for their employees in which they allow some customers ( good customers as per bank) also to participate ? The premium is not very high & being bankers they manage to wrangle good services from Insurance Companies.
I cannot recollect where I read about this.
I dont think this is true , ask it on forum to confirm : http://www.jagoinvestor.com/forum
Dear manish
please give your views on
1) critical illness cover in mediclaim policy
2) critical illness as a rider, in term plan
3) stand-alone critical illness insurance policy
which is better in long term and benefits of taking any two of these simultaneously
regards
maneesh
Hi Manish, thanks for the good information posted on the net.
Please note that am an NRI and my company provides the health insurance for myself and myself. In india i dont have any health insurance. In addition to the the HI which my company has provided, do i need to take private health insurance in india. I visit india once a 6 months. Please advice. Regards, mahesh
Mahesh
Only you can decide if you need extra health insurance or not . Just see how much health insurance you have and ask yourself if thats enough . Think about it
Manish , I am a 44 years old MNC employee & my organisation provides the cover of around 2.5 Lacs (for general hospitalisation) & critical illness cover of around Rs, 8 Lacs for my entrire family (my wife & daughter) . My wife is a Govt employee & she has the facility of free treatment for entire family in selected hospitals for any illness .This facility of hers will continue even after her retirement being the govt employee
Although we are properly life insured , but have not taken any extra Health insurance . Should we go for more Health Insurance , seeing our existing stable health insurance policies from our respective employers
Hi Sandeep,
It is high time you go for your own independent cover. Depending on CGHS or any other Govt. health scheme is not a sound financial planning.
From my experience, these are the drawbacks of depending on Govt. Schemes:
1. Many hospitals do not have all the medical facilities (mostly the advanced facilities) and there are major deductions, when treatment is carried out of the network of listed hospitals
2. There are limits. A CGHS scheme allows a maximum of Rs. 65000 for a stent for cardiac operations, whereas a really good one, costs around a lakh. Many hospitals are opting out of treating CGHS employees.
Chances of suffering an ailment rises after 40 years, it becomes more and more difficult after 45 to get a good mediclaim. We would therefore suggest you buy a mediclaim immediately.
Regards,
Sandeep
Good to see that you have got some good facilities, if you are going to get everything covered, then I think you can skip it
Hi Manish
I generally reads blogs at this website. I came to know about this post while searching for any good mediclaim policy. Fantastic article. thanks for this!!!
I want to take mediclaim policy (Family floater) option for me (33 years) and my wife (31years). I am confused which one to take as lot of options are available. Reading above comments but could not take decision. I shortlisted 2 finally after reading much.
1. United India insurence
2. Apollo Munich
Could you please suggest, with which I should go for. UII has a limit for daily expenses but Apollo doesn’t but it has bit larger premium. As generally people suggest that should not go with private options (Apollo). is this correct..?
What should I do please from the above. Need to have your valuable advise on this..
Thanks
Abhishek
Hello Abhishek,
Presuming, you do not have any ailments, or medical history, you have multiple choices, some of the good ones are Apollo Munich Optima Restore, Max Bupa Family First, Bajaj Health Guard and Oriental Happy Family.
Do go through the following article for steps towards buying the policy: http://jagoinvestor.dev.diginnovators.site/2011/05/health-insurance-buying-steps.html
Also: http://jagoinvestor.dev.diginnovators.site/2011/08/health-insurance-myths-india.html
Look for a Good advisor, who provides unbiased advise and claims support.
Abhishek
There is no problem with Apollo , you can go with them and they have recently came up with a good plan called Apollo Optima Restore . Its a good one and recommended. Read the policy document to get insights in detail
Hi Manish,
Thank you for your advise. As per your suggestion I assume, there should not be any problem in claim settlement from Apollo, if we are the genuine in asking claim. I get bit afraid in private option as we hear that private company ‘A’ has been overtaken by company ‘B’. should there be any such thing with apollo in future :-)..?
Yes Apollo Optima Restore is good option but creating very high premium. I want to take simple family floater option for around 3L per year. What you suggest please.
Thanks in advance.
Abhishek
Abhishek
Note that claim is never rejected if its within the rules , most of the rejections happens when things are not in rules and regulation . Most of the times buyers misunderstand the things and expect something which is not covered at all and then later say bad things .
Manish
My Query is with reference to Medclaim for individuals with pre-existing Critical Illeness & in particular to Medimanage.
While i as planning to take medclaim for my family & i also have pre-existing health hazard, i posted a query on medimanage mentioning the health hazard .
The response which i got is with mentioned health hazard ,no PSU /Private Sector insurance company will give me mediclaim which is quite surprising and shocking . I was under impression for any existing illness there will be a waiting period by the company usually 4 yrs.& probably they may charge a higher premium but denying a mediclaim altogether is nowhere on my mind.
Is that correct company refusing proposal based on existing health condition,also is there a universal list of critical illness ( ??) which all the companies follow for refusal .
Also isnt this should be a basic right of every individual to go for medical cover
While i appreciate the due dilligence and long term approach of Medimanage team & also when i communicated to medimanage rep. that even though my disesase come under your category of critical illeness but the same is not true as per my doctor & medical reports , he suggested to send him , my medical reports ( Which i sent to them right away) based on which he will go and check with insurance companies and come back to me. This again shows there customer centricity.Hoping for a positive response from there side.
Hello Rishikesh,
Insurance Companies are for-profit organizations and have the full right to deny coverage, as per their underwriting guidelines. There is no universal list, but proposals with existing critical ailments including ones related to Heart, Renal, Paralysis, Cancer etc. are denied coverage by nearly all insurers.
We are in the business of health insurance, and we would never want to refuse a customer, but the fact of the matter is that in 99% cases, people with existing critical ailments are denied cover by Insurance companies, and that’s what we mentioned to you.
This is precisely the reason, why we continuously recommend, in all forums, regarding, taking covers at the youngest age possible, at-least once you start earning.
We would suggest you to help us with logging a complete proposal including payment of premium to the Insurance company, for us to try and get a cover for you. Remember, there are just 1-2% chances of acceptance.
Regards,
Mahavir Chopra
Hi Mahavir,
Thanks for the reply , so should i log the proposal or wait for your representative ( To whom i have sent me medical reports) to come back .
Our representative will call you. Thanks.
Hi,
I am very new to this Health Insurance world. As many of us, i too was under the impression that Corporate cover would suffice. Thanks to this blog that changed my opinion.
I would like to take an insurance for me(32) and my husband(34). I have the following questions
1. What are the various aspects I should keep in mind?
2. I do not understand the these jargons – CO-Pay, Family Floater, etc
3. Would I be covered for Maternity in a year’s time if I buy the plan by May?
4. Can I claim for any tax benefits?
5. Also, if I dont claim, would my premium change?
6. What are the various riders that I shud be considering?
7. Can I split the coverage and take 2 policies instead so that I an share the premium with my husband?
Any other details that can better my understanding would be appreciated. Reading my questions, you would know that i am a novice in this field and trying to gain knowledge to save my wealth!
Thanks
Veena
Hi Rahul
I do agree with Mahavir (Most Insurance Companies settle genuine claims, as per policy wordings. The rejection of claims, we experience are purely due to non compliance with policy wordings, misrepresentation of facts in proposal form OR due to explicit exclusion in the policy.) BUT imagine a situation Mr A has taken a mediclaim policy for example 5 lacs Sum Insured and he after 5 days or 10 days hospitalised for Dengu and remain in hospital for 10 days. In this situation do you know mediclaim company will pay the claim?
before taking final decision you should know the WAITING PERIOD, Temporary Exclusions, Permanent Exclusions, Coverage, Sub Limits, Co-pay, No claim Bonus/No claim Discount.
Have you decided about Sum Insured ? ( or what is your Annual Income?)
Javed
Thanks for your reply Mr. Mahavir.
So, in keeping with my family profile, do you suggest me to go for Bajaj Allainz family floater ? Not with Apollo, or Oriental, or Star, or HDFC, or United etc. ?
Beacuse HDFC & United have a good Claim Acceptance Ratio ( as per i-save: dont know how reliable their rating is ), & so is Star ( as per HT-Mars survey ).
Could you please elaborate a bit, if possible ?
Need to finalise & close this by tomorrow EoD.
Thanks & Regards,
Rahul
Hello Rahul,
Most Insurance Companies settle genuine claims, as per policy wordings. The rejection of claims, we experience are purely due to non compliance with policy wordings, misrepresentation of facts in proposal form OR due to explicit exclusion in the policy.
Bajaj, Apollo, Max, Oriental, HDFC, Star are all good companies, which will not reject a genuine claim. You need to be educated about exclusions, so that you know what to expect.
Discuss your requirement, with an expert advisor in detail, explain him your needs, and then decide.
Good luck!
Hi,
I am 28, married & 1 kid; I am looking for 2 things:
1) Health Insurance policy i.e. Cashless Hospitalization Mediclaim(Family Floater)
2) Critical Illness Policy for myself
Like everyone else, I am covered under a Corporate Health Insurance Plan ( from my employer ).
Which is the best insurer in terms of claim acceptance & convenience & overall performance, so far ?
Second, should I buy this policy from PSU, Private, General Insurer, Heath Insurer, LIC or whom ]
Finally, are the policies like LIC Health Plus / Jeevan Arogya, good enough ? What’s you take on them ? Please suggest.
Thanks in advance.
Regards,
Rahul
Hi Rahul
Write your spouse age ans your city.
Javed
Hi Javed,
Spouse is 29 years, kid is 1 year & city is Bangalore.
I have shortlisted Apollo-Munich Standard, Star Family Optima, HDFC Ergo, United India & Oriental ( all Family Floaters ).
However, I have seen contradictory info regarding Apollo Munich & Star Allied.
Some say, Star Allied has highest Claim Acceptance ratio ( HT-Mars Survey ) & hassle-free service & Apollo has lower Claim Acceptance ratio, while some like i-save mention the reverse of it. Which one is actually better ?
Second, what is your view of HDFC Ergo, who as per i-save, have the best Claim Acceptance Ratio & Best Service, albeit higher cost ? Is this reliable enough ?
Can you clarify these things ?
Please suggest. Thanks in advance.
Regards,
Rahul
Rahul,
Claim Acceptance ratio, cannot be a core criteria to buy a policy. A PSU company like New India or Oriental will have a low claim settlement ratio, since it could be attracting many fraud claims or claims where facts have been misrepresented.
An Insurance Company which has a 100% claim settlement ratio, is not necessarily a good company, it could be a case, where they don’t have a good investigation mechanism to catch claims with misrepresentation or fraud.
A Survey can again be misleading, depending on how composite the survey participants are, and whether they represent the experience of a large population like India.
You need to talk to a good Neutral/Unbiased Health Insurance Advisor, understand and depend on his real experiences, to get a good understanding.
In my personal experience, I would rate Bajaj Allianz, as the best, solely based on claims experience.
Rahul
It would be better to ask directly to medimanage.com site on this or our forum : http://jagoinvestor.dev.diginnovators.site/forum/
Hi Manish
Apollo Munich Health Insurance Company is not accepting proposal from diabetic.
And
The Oriental Insurance Company Ltd is also not issuing a mediclaim policy to diabetic persons.
Only option left for Shiva is Max Bupa Health Insurance Company in which he can take Silver, Gold and Platinum Plan and Sum Insured upto 50 lacs.
Javed
Javed
I was not aware about that .. Does Max Bupa cover any diabetic person ? Wont they deny the policy ?
Manish
Manish
They will underwrite the proposal with following 3 options:
1 pass as normal policy,
2 pass with certain exclusion written on the policy or
3 reject the proposal
javed
Thank you Manish for such a wonderful portal and alos thanks to javed for helping me.
It’s true that Apollo Munich does not accept Diabetic cases, but Oriental does accepted ALL cases for Diabetes with us.
We have a very recent case with Max Bupa, where customer had Diabetes and Hypertension, went through Medical Test, and the proposal was denied.
Hi, I’m self employed and looking to take health insurance for my family. I’m single and my parents 54 & 49 are both diabetic and my father has hypertension. They use oral medication only and looking to take an insurance plan that would cover any ailments in future. We are looking for a good plan, where i could add my wife in future. Kindly advice.
Shiva
There is a new plan in market called Appolo Munich Optima Restore . Then you have options like Oriental Happy Family Floater and Max Bupa
Kanchan
Yea .. correct .. This health insurance will really help her incaes of some mishap
Manish
Thanks Manish. Would want something more conrete on it. Someone is telling me that the group medical policy that i am insured for through my organisation is something that can be changed to Individual policy if and when I leave the organisation and that this happens due to Potability facility.
My understanding is – Group policies are bought by the organisation and has nothing to do with individual when he is not with that organisation.
Only those policies which i buy on my own are allowed to be transfered to other company in case i wish to access potability for any reason.
I am looking for a complete clause of health insurance potability !
Can you help Manish ?
Hello Monika,
You can port your cover under the Corporate Policy (irrespective of who has paid the premium) to an individual policy with the same Insurance Company in the first year. You will be able to port into another Insurance Company in the second year.
The complete clause of portability is as follows:
Mahavir
THanks for Info .. i was not aware of this
Manish
Hi Mahavir,
The link is not working (at least at the time I am posting this message).
This portability provision from corporate to individual was a surprise to me. If it is without any killer clause/rider, this is a very pleasant surprise indeed. One of the reasons I have taken personal mediclaim (over and above the company provided one) is keeping post-retirement scenario in mind. With the kind of portability you indicated, I see no reason to continue personal mediclaim for post-retirement purpose. Any comments?
Hi Sambaran Mitra
If you have personal Mediclaim over and above the company provided Mediclaim is always a good option, it increases your SUM INURED.
Portability is the option you can use to transfer your policy but you cannot compel a mediclaim company to accept your portability proposal. If anybody has taken claim or has critical illness new company will not accept the proposal. Nobody can compell to a Health Insurance Company to accept a bad risk.
New proposal or portability is for those who are medically insurable, but if you have life time renewable policy the HI company cannot refuse to renew the policy because of illness.
Javed
Hello Sambaran,
Portability is an option, except for the the following conditions:
1. Young Members, that is all members are below the age of 45.
2. You have a claim in your existing policy.
3. You have a new ailment contracted during the continuation of the existing policy
4. You have a pre-existing ailment mentioned in your existing policy.
The catch in Portability is that it would always be subject to underwriting guidelines of the Insurance Co. The proposal for portability can be rejected or additional conditions added before acceptance.
Portability from Corporate is not the answer for coverage post retirement.
Javed and Mahavir,
Thanks a lot for your replies. It helps.