Everyone is so desperate to buy a child plan (example). The features of so-called children plan are bundled in a way that it looks magical, as if there can’t be any other product like a child plan and hence, we pay much more than the price it really deserves most of the times. So today we will see how we can create your own child policy by combining term plan and other investments like PPF, FD or a Mutual Fund.
When you hear “Child Policy”, It looks extremely attractive. It gives you money on your death, It gives yearly income and it also gives you money on the maturity of the plan (generally when you child is ready for higher education) . So the point is that a child policy is so much in demand and attracts investors because of its features. However there are some issues with child plans in market. They come with high costs, rigid structure and very less control over it. Traditional Children plans (which are endowment or money back type) mainly do not deliver of returns front and ULIP children plans come with high cost .
So what can you do now ? Can we create a child policy on your own by combining Term Plan and Investments in some separate instrument, in a way that the Term Plan will take care in case of your death and investments will take care of higher education cost in case you survive.
So just like you pay a yearly premium for a Child policy, even in this case you will pay a fixed amount every year. A part of it will go as Term Insurance Premium and rest will go into investments. But in this case the term plan will also open ways for yearly income, as well as future big time expenses for child higher education as well.
When you are not there, the amount received by family from term insurance can be invested in such a manner, that it can provide a yearly income + lumpsum money NOW + Lumpsum money in FUTURE. Lets us take an example and see how it will look like. Suppose you have a 1 yr old daughter for whom you want to create a Child Policy like structure, and you want to achieve these 3 things.
| 1. Lumpsum Money | If you are no more , family gets 50 lacs upfront as lumpsum. |
| 2. Regular Income | After your death, your family should get Rs 50,000 per year separately for your daughter education for next 20 yrs and this Rs 50,000 should increase every year by 9% (so that inflation is taken care of) and assuming this money will grow at 8% return (FD) |
| 3. Money for Higher Education | When your daughter turns 21 yrs old and is ready for her higher eduction, she should get another 25 lacs at that time. |
In order to achieve the 3 things mentioned above , you need to buy a term plan for Rs 65 lacs (Sum assured) and start investing Rs 50,000 per year in something which gives 8% return on annual basis. Apart from this, you will need to clearly define to your family what actions they need to do once you are no more (these are simple tasks like opening a FD or investing money in PPF or balanced funds). The yearly premium for this structure would be around Rs 60,000 (50,000 investment + 10,000 premium for term plan) . Lets us see how this structure will be helpful .
If case of death (Your family gets 65 lacs)
- 50 lacs can be taken out as lumpsum
- 5 lacs can be invested one time to get 25 lacs at the end of 20 yrs
- 10 lacs can be invested one time to get a yearly income of 50,000 increasing by inflation figures!
Incase you survive
- Your investments of 50,000 annually will create a corpus of 25 lacs at the end of 20 yrs anyways
Lets us see this same example through a picture, which will clearly illustrate how this 60,000 premium payment will create a Child policy kind of structure and how it will help you in case of death and survival.
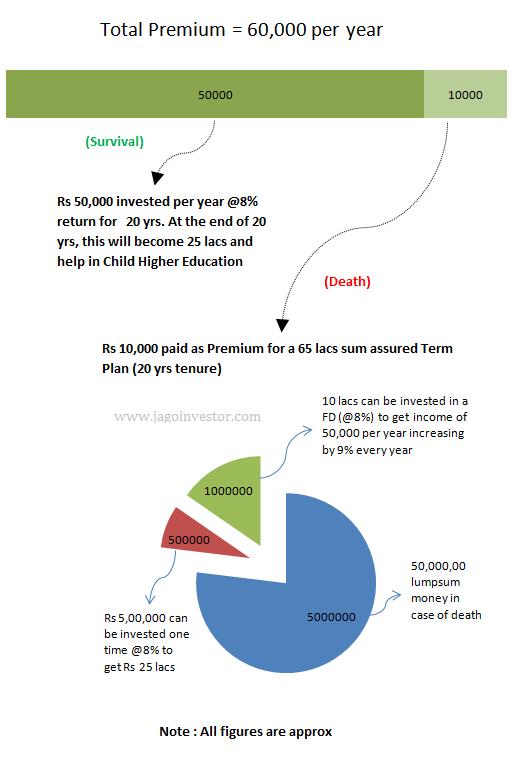
So using this structure you can achieve what a child policy provides. However this whole method has its own pros and cons. There is a lot of flexibility in this structure which a child policy does not have. However this kind of structure would need some level of trust and you will need to instruct your family about it and what they need to do incase you are not around. I think if you are preparing a will, you can clearly mention what needs to be done with the term plan money, so that family members can take those actions.
Download the Calculator and Start Planning your child Policy
Below is a calculator which you can download and punch in your numbers, the calculator will tell you how much term plan you need to take and how much investment has to be done per year. The expected return and inflation is decided by you. So if you want your family to put the money in FD or PPF after you are there around, then put the return expected as 8%, if you want it to be in Balanced Funds put 10-11% and incase of Equity Mutual Funds, put 12-15%. Also note that the premium for term plan will depend on the company you choose for taking a term plan (LIC is coming up with its term plan in few weeks as declared by them recently).
Download Child Policy Calculator Here
Comparison with Child Plans in Market
It’s important to see what is the difference between the child plans in market and this custom-made child policy by combining term plan and investments
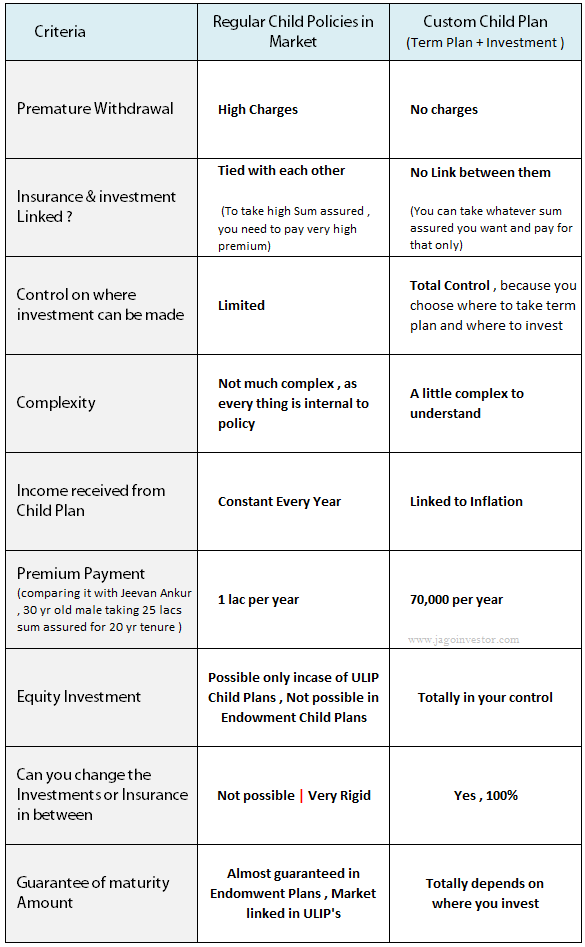
Comparing it with LIC Jeevan Ankur
Lets compare this with LIC Jeevan Ankur Policy. If a 30 yr old male has to take a 25 lacs policy for a tenure of 20 yrs, He will have to pay premium of Rs 1,00,000 per year (approx) . In case of death, his family will get 25 lacs + 2.5 lacs income per year till maturity + 30 lacs of maturity (assuming 20% loyalty addition) , incase the person survives, he will get 30 lacs anyways on maturity.
This same thing can be achieved if a person does a 60,000 per year investment in PPF or FD (assuming 8% yearly return) and taking a term plan for Rs 55-60 lacs for a premium of say Rs 10,000 per year (for most company, the premium is 5,000 but lets assume LIC online term plan is taken which will come in few weeks now). So he has to pay total 60k + 10k = 70k per year to achieve the same results, with a lot of flexibility.
Do you think this whole strategy of creating your own child policy is of any use? Do you think it’s too complex? Share your views.
Hi Manish.
Excellent article as always.
I was also approached for some child plan by my financial advisor. But instead of going for it I opted for the combi ation of term plan and mutual fund (HDFC Children’s Gift Fund – Investment.
I hope this decision of mine has put me in the right direction.
Hi Manish
I’m not supposed to go for Mutual funds or SIPs as my religion doesn’t allow it. In order to save for child education, request you to guide me on what are the other options that are available in market. I also have purchased two term plans, 50L and 60L each so term plan option is no longer available. I want to invest some amount per annum to get approx 50 Lac after 10 years. Please guide.
Cant you go with direct stocks also ? Because if thats the case, then the only option for you would be FD ! .. and thats not a good choice for long term investments.
Thanks for a quick reply Manish. Yes direct stocks or any kind of investments in stocks is not allowed in Islam, I was really hoping to know options other FD and PPF.
In that case you can invest in Debt mutual funds, They invest in debt options like corporate and govt securities. Its not Stocks !
In case you are new to this, my team can help you with setting up everything from start to end. Just fill up http://jagoinvestor.dev.diginnovators.site/start-sip
Thanks for reply Manish. However I wanted to know whether I can go for Bajaj Allianz future gain plan that is based on shariah funds. Do you recommend to go with it in terms of good returns.
Cant comment much as I have no idea about it !
Hi,
Nothing better than this, one of the best articles i have read.
Simplified everything.
Thanks for sharing
But with the calculation shown in comparison with LIC Jeevan Ankur policy.
Ankur seems to be a better policy.
Glad to know that ShekharRathore ..
Dear Manish
I am 41 yrls old and I want a child policy for my 7.8 yrs old daughter, i can invest Rs. 2 lac annually…Plz advise which would be the best policy
We dont think children plans are the best thing here. You should build a corpus in mutual funds
Hi Manish. Very good article.
I have 3 LIC policies. Since for 2 of them , I have paid premiums for 13 and 7 years respectively, I think it’s best to continue to pay till its premium term ends.
For the 3rd LIC which is a Child Career Plan, since i have paid 3 premiums and the 4th one is due this month, i am thinking of making it as “Paid Up” and then going for the combination of a term plan and a PPF (or PPF + Mutual Fund).
Let me know if the decision is a good one or not.
Thank you.
Regards,
Manish Wadhane
Yea , keep paying now till the term ends
Hello Manish,
I want to know about full life term plan. You have any term plan for whole life. My D.O.B.02/02/1988
please suggest me.
As far as I know, there is no term plan like that !
The maximum duration is provide by LIC term insurance which is 35 years coverage maximum 75 years of age. Rest ICICI, HDFC etc provides maximum 30 years coverage, but in LIC there is no additional riders.
Manish Bhai Can you elaborate below line by you ? how we will achieve this increasing in income by inflation figures ?
“10 lacs can be invested one time to get a yearly income of 50,000 increasing by inflation figures!”
Dont take it literally . I didnt mean that there exists some product which will do that for you. Its only theoritical !
It really seems good article . i have one question .
In your example how we will achieve “10 lacs can be invested one time to get a yearly income of 50,000 increasing by inflation figures!” ? Does your excel sheet is designed to calculate this inflation part too ?
Yes
Hi Manish,
This is very nice artical..thanks for that.
I have bought ICICI pinnacle super L with highest NAV B in Nov 2011.
its 5 years and each year 50k premium.
i paid 3 premium and not sure if i should continue OR stop paying premium?.
Can you please guide on this?
Is it Highest NAV plan ?
Dear Manish,
i read your valuable article, Im 32 yrs old,I like to invest monthly 3k or annualy 40k over the period of 10 – 15 years for my 2 yr girl baby, my intention is to get monthly benefits after the maturity period and it will help her for education expenses.
Thanks
Good point , then you can invest in PPF ..
Dear Manish,
I was feeling proud that I am also thinking like you.:-). But you have done a great job to create good example. Can you please guide me that from where I should buy the term plan,online/offline, and sum assured amount? My age is 30 years.
Thanks
Manish
You can take a 1 crore term plan from HDFC or Aviva/SBI
buying multiple term plan would be helpful.
I have 50 lakh term plan from SBI and 30 from SBI, 20 from Max life
****50 lakhs term plan of LIC. The trusted insutitution
Hi Manish,
I have taken tata aig maha life gold plan for my kid i have paid 2 year premium now i ‘m thinking of stopping and doing the process as mentioned above.
Kindly suggest should i go ahead and do the same
Yes you can go ahead if you are not satisfied with it .
Dear Manishji,
I had logged in today to search for a child plan for my 5 year old son and going through your article and calculator, I am completely clear on what I will do now. I already have a Term Plan from AVIVA of 1 crore, so now i will go for SIPs (Monthly Rs 5000-7000 for 20 years) to create the corpus. I have 2 questions:
1) Can I take SIPs in my child’s name?
2) Can SIPs be taken for 20 years?
3) Please suggest some good SIPs for long term?
Regards,
Amit Gehani
great !
1. Yes, you can , but why are you doing so ? What is the advantage ?
2. Yes, but whats the use of it, you will not run a SIP for 20 yrs in same fund, it has to change later, so better take it for 2-3 yrs .
3. Quantum long term equity , HDFC equity , HDFC Prudence are good one !
Manish
Hi Manish,
You have mention Term plan of LIC. I checked LIC site but couldnt figure out the exact plan u r talking about. Could you please help me to find out?
Also please provide information on various Term plan which i can look into.
We are talking about AMULYA JEEVAN plan from LIC , its a term plan above 25 lacs sum assured !
Dear manish,
i am planing for my daughter secured future.what about the jivan ankur LIC,i already invested in hdfc young star plus policy (its unit link) 3 years completed but as per market, policy performance not good so i stop my pa premium its 50000,so i planing to invest this 50000 for my daughter secured future, so please guide me how i can invest in different sector for long term with good benefit.
kalpesh
I suggest mutual funds in long run
Hi,
FD is better option for wealth creation but TDS will reduce the benefits.
Is it still better than other tax free child plans?
Can we make single FD for long term in childs name?
I think its better for those people who cant manage policies like ULIP’s .
Dear Manish Sir,
i m become uncle in last month and i want to give a gift as a education plan to my child for his bright future.
Can u suggest me, which one time investment plan(Single premium) i bought for my child. And also suggests its benefits.
Warm thanks
I seriously discourage your from buying regular policies from market . Rather than a policy, better create a FD on the child name .
Hi Manish,
Can you give your views about Edelweiss Tokio Life – Education plan ? It sounds good.
Also, can you shed some lights about the company ?
Regards,
Pradeep.
If its not a term plan, then just avoid it .
Hi Manish,
When we talk of MF over other investments like ULIP or Child Plans, we kind of hide away the facts that-
investment in MF does not enjoy TAX rebate and
the income returns (ranging 7-20%) is Taxable
My query would be-
So when you say 12-15% returns, what will be the actual/average figures after tax deduction?
And an actual/average loss figures for not having put the money in TAX saving tools?
P.S. I am definitely not against ‘Term Insurance + MF’ investment idea.
Thanks
Sanju
Equity mutual funds profits are TAX FREE 🙂 .. Its capital gains and its not taxable after 1 yrs
Thanks for all your Free Gyan Manish!
Hi Manish,
Thanks for detialed explanation.. what is the correct age to take Term Plan? Currently I am 27years old, is this the right time for me to go for Term Policy.
The correct age is when some one is financially dependent on you !
Great manish sir.