What do you do when you want to take a very high health insurance cover like 20 lacs? Is the only option a regular health insurance plan? In this case, you can use top up health insurance plans, which are one of the best ways to enhance your health cover after a certain threshold? In this article lets understand how top up and super top up health plans work and how they benefit you. So we will understand both “top up health insurance” and “Super top up health insurance” in this article, but let’s understand first what the meaning of “Top up” is, in general.
What is the meaning of “Top Up” Cover ?
A top up cover actually covers you after a “threshold limit” is already exhausted or used. To give you an example lets say you have a top up health cover of Rs 10 lacs sum assured with the threshold limit of Rs 5 lacs, in which case the policy will only cover your expenses beyond Rs 5 lacs only. If your claim amount is Rs 8 lacs, then it will only pay you Rs 3 lacs (8 – 5), and NOT Rs 8 lacs total. That’s the main difference between a regular health cover policy and a top up cover.
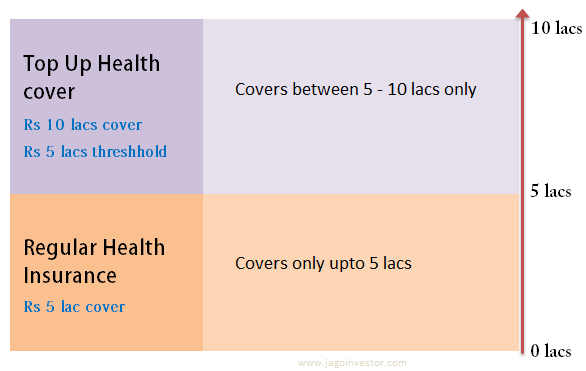
So now if you already have a health insurance cover of Rs 5 lacs sum assured, then you can take a top up cover up to Rs 10 lacs with threshold limit of Rs 5 lacs, that way you will be covered up to 10 lacs. The first policy will cover you up to Rs 5 lacs, and the top up cover will cover you for the 5-10 lacs range. You can understand that more clearly with following image.
Suppose you have following 2 policies.
- Policy A – Regular Health Insurance Plan with Rs 5 lacs sum assured.
- Policy B – Top up cover of Rs 10 lacs with threshold limit of Rs 5 lacs.
Now let’s take this same example and try to understand how Policy A (Regular Health Insurance) and Policy B (Top up health insurance) will pay you in 3 different scenarios, just to make sure you fully understand how top up health insurance policies work.
Scenario 1 – Claim of Rs 3 lacs
In this case, the first policy will cover you for full Rs 3 lacs, as your policy itself is for up to Rs 5 lacs.
Scenario 2 – Claim of Rs 8 lacs
In this example, the first plan A, will cover you up to Rs 5 lacs, but if your hospitalization expenses go to say Rs 8 lacs, then the first policy will only pay Rs 5 lacs, but the second policy (B) will cover you for the rest of the Rs 3 lacs, which is above the threshold of Rs 5 lacs.
Scenario 3 – Claim of Rs 12 lacs
In this case, first policy A will pay you Rs 5 lacs, and the second policy B, will pay you next 5 lacs only, because you have taken a top up cover of up to Rs 10 lacs only. So the Rs 2 lacs extra, you will have to pay from your own pocket.
What is Super Top up Cover ?
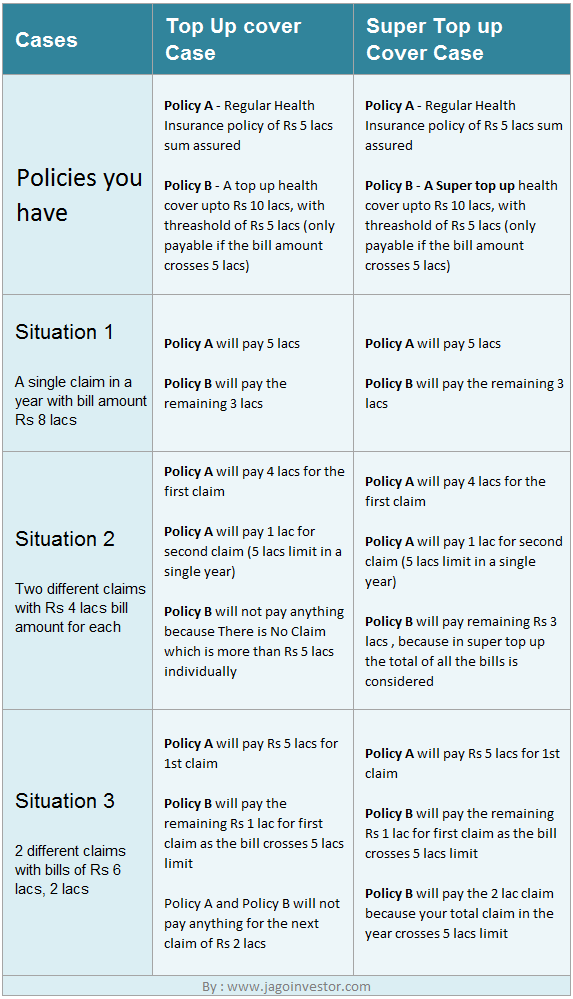
Just like a top-up cover, there is something called as Super Top-Up cover, with a very small difference. A top-up cover will pay you only if your claim amount (bill for a single hospitalization) is above the threshold. Like, in our example above, the top up cover will help you only when your bill is above Rs 5 lacs each time, only then it will come into picture, like in the case of the Rs 8 lacs bill, then the top up cover will pay you an additional Rs 3 lacs. But if you have two bills of Rs 4 lacs each, then the normal Top up cover will not help because no single bill amount is above the threshold limit of Rs 5 lacs.
That’s where Super top up plans come into picture, which takes into consideration the TOTAL of the bills in a year and not just the single instance. So in case of two bills of Rs 4 lacs each, your total bill is Rs 8 lacs (above threshold limit of Rs 5 lacs), then Super top up cover will pay you, where a Top up cover will not.
Let me clear that with a more detailed example by using the chart below
Companies Offering Top up and Super top up plans in India
Companies offering Top up
- Apollo Munich OptimaPlus
- Bajaj Allianz Extra Care
- Bharti Axa High Deductible Health Insurance
- ICICI Lombard Healthcare Plus
- Star Health Super Surplus
- United India Top up Health Insurance
Companies offering Super Top up
- United India
- HDFC Ergo Health Suraksha (offering to bank and credit customers, currently)
Let me give you a comparison chart of the current Top up health insurance plans in India at the moment. Not many Super top up plans, so they are not in the chart while comparing.
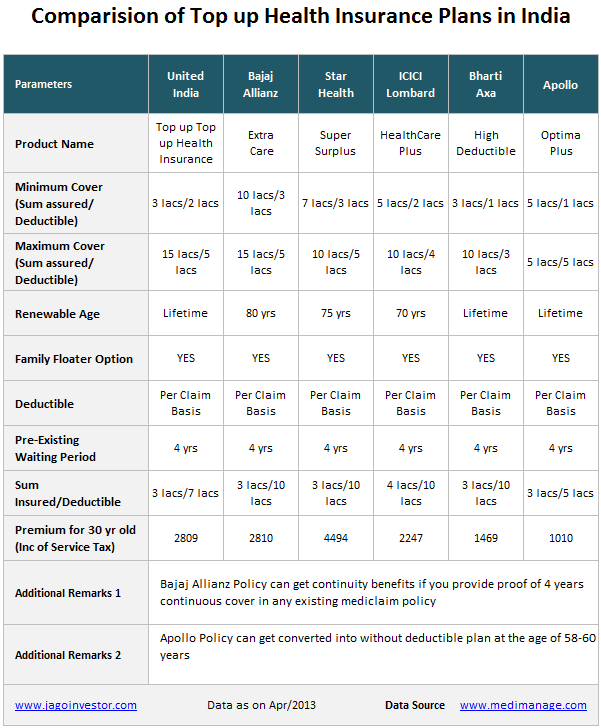
Super Top up Cover for Employees having group cover from Employer
A lot of salaried employees already have a group cover from their employer and they feel that they should not waste their money in a separate health insurance policy (which is not quite a right way of thinking, and you can read this article to know why I say that.) A top up cover is a very useful way for those employees to extend their cover beyond a point.
Lets say you already have a 5 lacs cover from your employer, but you feel that it’s insufficient and you wanted to have a cover up to Rs 10 lacs. Now, one way of doing it is to take a separate cover of Rs 10 lacs, but you can take a top up cover of up to Rs 10 lacs with threshold of Rs 5 lacs (as you are already covered from your employer up to 5 lacs). This way you will be covered up to 10 lacs. But understand that in that case you will have to claim your expenses multiple times.
Additional Health Insurance cover or Top up cover – Comparison
Just give me pointers, I will write about it, or just send me an example where we are comparing a 10 lac cover with A 5 Lac cover + top of 5 lacs
When does a top cover policy makes sense – Hear from experts
So is topup or super top up cover the best option to upgrade your health insurance coverage ? No !. Here is what Mahavir Chopra, a health insurance expert suggests –
Most Insurance advisers recommend a top-up plan to upgrade your coverage. In terms of convenience of purchase and claims, we would recommend upgrade of the same health insurance policy, as the best option. This is of-course, provided you are happy with the policy terms and services.
The second best option would be to compare available options of Super Top-up with option of Additional Mediclaim Policy. If the premium is more or less the same, we would recommend additional policy more than a Super Top-up.
After all the above options, look for the option of a simple top-up to increase your cover. Be sure you are aware of the fact, that this option is more useful in the very long term (6-10 years), since it will trigger only when your one claim goes above the threshold/deductible mentioned in the policy.
Features of Top up Health Insurance Plans
Let me tell some more points and features about the top up plans so that you are more clear about it and if its useful for you or not
1. Cheaper than regular health insurance plans – You have already seen that they are cheaper than the regular health insurance plans because they cover you only beyond a threshold, the probability of which happening is very less.
2. You can buy it from anywhere – You can buy a top-up cover from any company, there is no compulsion that you need to have another cover from same company. In-fact there is no requirement that you should have another health cover at all. You can just take a top up cover even if you do not have any other health insurance product.
3. Available with the option of individual and Family Floater Cover – A top up cover is available as individual cover and also as a family floater. So you can extend the cover for your entire family. Just that some policies might consider parents into family floater and others might not.
4. Concept of Pre-existing illnesses and Exclusions – Just like a normal health cover policy, even a top up cover can impose the restrictions on the pre-existing illnesses and exclude the diseases which they feel they do not want to cover. Also some top up covers might not cover pre and post hospitalization expenses. Some policies like Bajaj Allianz Extra Care provides continuity for already existing main policies. For instance, if you have a policy for 10 years with say New India Assurance, and you are buying a Top up from Bajaj Allianz, you will get continuity for the 10 years on the top-up and hence the waiting periods will not apply to you.
5. Tax benefits under Section 80D – You can get the tax benefit under sec 80D for the top up cover policies
6. Cashless facility would be difficult – I am not sure on this one, please guide! You need to follow the same cashless procedure, when your hospital bill exceeds the sum insured of main policy. If you are aware in advance about the high hospital bill, ensure you intimate at the time of admission itself.
Are you looking for extending your health insurance cover using a top up or a super topup cover ?
Hi Manish, i think there is a mistake. as per my understanding.
if i buy a top up policy of sum insured 10 L with deductible 5 L. and i have a base policy of 5 L so it means i am getting total cover of 15 L.
from your article getting impression that we will get total cover of 10 L only.
No , its a 10 lacs coverage only.
The base cover will cover 0-5 lacs
10 lacs cover with 5 lacs deductible will cover 5-10 lacs cover.
However note that some companies use words differently .. Check with company exact thing
I think they are suggesting correct. You should take a seperate plan for your mother for you . Have you already taken the plan?
Thanks Manish for reply. Still I haven’t taken the plan, since I didn’t find any answer for my question asked above.
Hi Manish…want to buy family floater plan.but confused between supertop and regain plans…hdfc ergo gives both plans.so to increase cover which is to opt …base plan+ supertop up / plan with regain option.pls comment..thanx
Hi Prashant
Thanks for asking your health insurance question. We will get on call with you and help you resolve your query. Please fill up your details at
http://jagoinvestor.dev.diginnovators.site/services/health-insurance
We will call you back
Manish
Hi Mohit ,
Its great way to go and understand the insurance ,when lots of options available then more confusion creates.
We are three of in family myself (age 44) , wife (age 43) and son (age 3)
My queries are below:
1) I have base policy of 10 lakhs ( Family floater )(premium Rs.38000/-) want to reduced this year by Rs.5 lakhs (premium Rs.23000/-) and go for super top up Rs.20 lakhs (premium Rs.5000/- ) – Is it advisable – since it saves on premium as well as increasing coverage . I will get coverage of Rs.25 lakhs in a premium of Rs. 28000/- , instead of taking 10 lakhs in Rs.38000/-
2) Or should i take super top up separately for me and son as family floater , and one individual for my wife .
3) what is the concept of threshold limit ? If I am not wrong then if i have 5 base + 20 super top up then over all i get 25 lakhs coverage , with first 5 lakhs exhaust, and then remaining from super top up .
4) If i am not going for separate super top up for my wife , and continue with family floater – then in that case if in a year one family member claim for any critical illness , then can another family member will claim for the same in that year , or it will exhaust .
please advise urgently ,as my policy is on renewal .
Thanks and regards
2)
2)
Hi Sunildutt
Thanks for asking your health insurance question. We will get on call with you and help you resolve your query. Please fill up your details at
http://jagoinvestor.dev.diginnovators.site/services/health-insurance
We will call you back
Manish
Hi,
If the base medical policy gets changed, what happens to the top up cover?
I am covered from my employer for medical insurance and thinking of buying an additional top up plan, what will happen if i change to a different employer which will have a different sum assured
There is no link between base policy and top up cover. Top up cover is independent of it .
If you take a topup cover of 10 lacs with 5 lacs deductible, that only means that if expenses are above 5 lacs , like say 8 lacs, then on producing the bills etc, they will settle the rest of the claim . thats all !
My father has new india assurance parivar mediclaim poilcy sum insured 3 lakhs, however the agent was saying that if hospitalized approx 50 % is refunded. So if he takes a top up of 5 lakhs and the hospital bill is four lakhs. The first 3 lakhs would be covered by New India assurance and the remaining 1 lakhs by the top up plan. But from the initial 3 lakhs he would still have to pay 1.5 approx from his own pocket right? or is there a way out?
I dont think there is a way out . You shouls take a totally new separate policy for this which does not have any copay
Thank you for the reply
Can you give me the list of Top up Product and Super Top Up products currently available in Indian Market ?
Hi ChiragJain
Thanks for sharing your health insurance requirement. I think the best think you can do is leave your details at https://www.coverfox.com/jagoinvestor . And you will get a expert assistance on selecting and buying the right policy for you.
You can then take the decision.
Manish
I have really have a big doubt. In case of necessary will these companies pay the expenses fully or try to disown the responsibility of payment of expenses and try to make profit? This doubt has come to me because of an incident I came across. A gentle man who has accident insurance died on accident. His wife, who has school going children, submitted claim papers. One fine day, a person from the insurance company came and said she will get only few lakh rupees but not full insurance and insisted her to sign papers for that lesser amount. Probably he offered leser amount seeing her dare need for money. She refused to sign and informed the agent. The agent insisted for settlement for full claim and told the insurance company that if they cheat the public like this no body will do insurance. With his interference only the woman got full amount. He is an exceptional agent as generally these agents will not see the face of the insured when in need.
I am not sure if this case is true or not. Because is not how it operates. THe claim is settled in full only !
Hi Manish,
I have a confusion regarding this specifically related to limits and thresholds.
My base insurance is 8Lakhs from New India which has a limit of Rs 24000 for cataract and the top UP from New India (with threshold of 8L) the limit for cataract is 50,000.
So my question is how much exactly will I get if the doctor charges 40000 for the cataract operation.
Will 24000 be passed under main policy and remaining 16000 under top up OR
I will get only 24000 and nothing under Top Up since threshold of 8L is not crossed.
Regards,
Vijay
Yes, top will not come into picture in your scenario . It comes in to picture only when your bill is above the threshhold limit !
I have a query regarding Super Top Up Policy and Co-payment.
Suppose I have an existing insurance with comp. A for 4 lacs with 20% co-payment. Now, I want to buy super topup of 5 lacs. How will that work out ?
My existing policy (from A) gives me upto 4 lacs for claims upto 5 lacs (20% i.e. 1 lac has to be borne by me).
Does, the situation change if I buy a super top up of 5 lacs from comp. B ?
My guess is that, I will still have to pay 1 lac co-payment and super topup will come into picture only when I exhaust 4 lacs from existing insurer (i.e. through bills of 5 lacs in a year).
I need clarification over the same.
Thanks
Nikhil
You can buy a super topup with deductible of 4 lacs in that case.
I think the best think you can do is right now is leave your details at https://www.coverfox.com/jagoinvestor . And you will get a expert assistance on selecting and buying the right policy for you.
You can then take the decision.
Manish
Sir,
you mentioned that “In-fact there is no requirement that you should have another health cover at all. You can just take a top up cover even if you do not have any other health insurance product”
Kindly provide more info on above quote.. (i think in that case we have to pay the bill upto threshold)
also pl confirm whether above is true for super top up also.
thanks & best regards
Arun Gupta
Yes, its true for super top up .
You can just take a super top up with 10 lacs insurance with 5 lacs deductible , means you have to bear the expenses upto 5 lacs and above that upto 10 lacs the super top up will pay off !
Hi Manish,
Thanks for a very helpful blog. I really appreciate the detailed info. that you have provided and also your prompt responses to queries raised.
I (age 42) have an existing policy with my mother (age 67) from United India Insurance. My sum assured is 5 Lakhs while it is only 1 lakh for my mother. My father(age 73) has a separate policy with sum assured of Rs. 50 K only. I feel that all the sums assured should increase thinking long term (especially for me). I have following 2 questions –
1. In my case, I can take the super top up from United India – as per the above article. (I am single, so family floater is not applicable). I however feel that taking the long term view, this floater provided will be insufficient. What is the way out – Is it better to go for another basic + floater policy from some other company – so that together the limit is higher or should I take only additional floater policies of United India + some other Company ? (By long term view, I mean that currently I am healthy but I do not know about the future).
2) What can be done in case of my parents ? They are healthy as of now but future is uncertain. I am told that because of the age, United India will neither increase the sum assured nor will they give any top up.
Kindly advise.
Thanks,
Salil
In both the cases (for yourself + parents) try to increase the cover to 5/10 lacs from existing insurance company . Super topup is to be taken once you have a base policy for a good sum assured.
I think the best think you can do is right now is leave your details at https://www.coverfox.com/jagoinvestor . And you will get a expert assistance on selecting and buying the right policy for you.
You can then take the decision.
Manish
Hi Manish,
Thanks for your advise. Just need one more clarification – In my case, I already have a basic cover of Rs. 5 Lakhs from United India Insurance. I feel it is insufficient but United India has refused to increase the same. In this case, should I go to some other Govt. / private insurance company and take additional basic cover of say Rs. 5 Lakhs ?
Yes, its suggested . You can go for a super top up policy at a small cost.
I think the best think you can do is right now is leave your details at https://www.coverfox.com/jagoinvestor . And you will get a expert assistance on selecting and buying the right policy for you.
You can then take the decision.
Manish
Dear Manish,
Your blog confused me. After considerable research on the internet and going through the explanation as given in L&T super top up policy brochure, I deduce the following,
There is an inherent flaw in the article.
Reproducing a part of your article, as below to point out the same,
“Suppose you have following 2 policies.
Policy A – Regular Health Insurance Plan with Rs 5 lacs sum assured.
Policy B – Top up cover of Rs 10 lacs with threshold limit of Rs 5 lacs.”
This basically means you have a total coverage of,
(5L + 10L) = 15L ( Base policy + Super Top up policy)
and not 10L as stated in the article.
Therefore in the given scenario 3: Nothing would be payable by the claimant until the claim amount exceeds 15L.
Threshold limit on the Super top up or Top up policy signifies that these policies would trigger only when they are above the specified threshold value, but the sum Insured is over and above the base policy.
Another example, United India Insurance Super top up policy premium chart says 3 L super top policy with threshold value of 3 L. As per the above article super top up policy would never get triggered.
These are my observations logically based on the policy docs of different companies.
Amit
Hi Amit
when we say 10 lacs of top up policy with 5 lacs of threshhold, we mean that the coverage is from 5-15 lacs band .
So if bill is less than 5 lacs, the first policy pays.
If its 8 lacs, then 5 lacs is paid by first and rest 3 lacs is paid by top up
If its 20 lacs, then 5 from first, 10 from second and rest is borne by you!
I hope you get it now ?
Hi Manish.
I’m planning to get an ICICI Lombard iHealth family floater plan for my parents and sister along with an L&T Super Top Up. I want a total cover of ₹15 lac or more. Does it make more sense to go with a ₹10 lac base policy and ₹10 lac super top up, or should I make it ₹5 lac base and ₹10 lac super top up?
I also have some feedback for you: you keep recommending Coverfox in your posts but you never seem to mention anywhere that there are other insurance companies apart from the ones Coverfox deals with. In all my research (looking at Mint’s health insurance ratings and checking out ICICI’s historic claims settlement ratios and time taken to settle), it emerges quite decisively that ICICI Lombard is the best health insurance provider in India by a wide margin. And yet, going by your recommendation, your readers would never even hear about it. I’d love to hear your thoughts on this.
Thanks for running this blog, it’s a singularly excellent resource!
Aayush
I would suggest going for 10+10 combination. Regarding COverfgox. Note that coverfox is a broker which we are recommending. We do not recommend insurance company because it depends on your requirement. Regarding ICICI Lombard, It might be great in few aspects, but overall if you see there are some really good plans from Religare, L&T , Max bupa … so it differs from case to case.
Dont go with ratings, its nothing but an algorithm run for few parameters, which gives a broader idea about a product. It cant be a criteria for selection. Buying a product based on Rating is like hiring an employee based on their CGPA .
Manish
Hi Aayush arya,
How was your experience with L&T Super Top up? Have you done enough research on it? Will you recommend me to go with it?
Hi Manish,
Nice and detailed info.
I have one question. if Super top is going to help in case of either single or multiple bills, then why one will go for TOP up. Everyone will by Super TOP only. I want to understand if there is any advantage of TOP UP policy over SUPER TOP policy? pl. let me know
–kishor
Low premium 🙂
Hi, I am a long time follower of you. Is your association with Medimanage over, as you are recommending your readers to visit Coverfox?
Yes KK
Thats true, at any point of time, we want to associate with someone who is best in its category. We feel Coverfox is really good for insurance needs. HOwever incase you have personal comfort with other company, you should go to them ..
Does a super top of 15 lac with 5 lacs threshold has any advantage with a 10lac base ? I have an existing 10 lac mediclaim from united india and I am planning to for 15 lac super top with 5 threshold from United india
I think 10 lacs base with 5 lacs extra top up is better . I would like 10 lacs option
1. United India has a super top-up plan, Insurance cover 7 lacs and threshold limit 3 lacs. This means total insurance cover is Rs. 10 lacs ( 3+7) or 7 lacs ( 3+4).
2. Can we combine 2 policies. For example if I have one policy of 3 lacs and it gets exausted and I have another policy of 2 lacs. Can two differ policies be used for one treatment in continuation.
Yes anurag
Two policies can be used for a single treatment
Hi, could you please clarify the first query from Anurag, regarding total insurance sum, is it 10 or 7?
Thanks in advance
I have a 3 lakh base policy from employer covering me,son,wife and parents.i am planning to take super top up Apollo Munich super top up family floater but it covers only me,son and wife…so my question is what will happen if for a 7 lakh super top up plan and lakh deductible if my parents utilise 2 lakhs of base policy and then after 5 lakhs claim comes from me.so will I have to bear 1 lakh or 3 lakhs as parents are not covered in super top up..kindly guide or suggest super top up with parents also included along with wife and son
Hi sameer
Thanks for sharing your health insurance requirement. I think the best think you can do is leave your details at https://www.coverfox.com/jagoinvestor . And you will get a expert assistance on selecting and buying the right policy for you.
You can then take the decision.
Manish
I am already having 5 lac health coverage from Oriental Insurance for me ,wife and son . I am 59 yrs. . I want to have a super top up plan for another 5 to 10 Lacs. Please advice about the best companies and plans.
Thanks
Hi Sheel
Bajaj has a good top up policy and even some more companies have it, I suggest that you reach out to https://www.coverfox.com/jagoinvestor/ and leave your details there . You will get dedicated support from Coverfox on this .